LKQ Corporation faces heightened investor concern after regulatory and earnings setbacks, as its stocks have been trading down by -22.12 percent.
What Traders Need To Know
- LKQ pre-announced weak Q3 2026 results driven by severe underperformance in Europe, including sharp margin compression and large impairment charges that pushed continuing operations into a net loss.
- The company issued preliminary Q3 adjusted EPS guidance of $0.47–$0.53 versus Wall Street consensus of $0.69 and guided revenue to about $3.32B, below the $3.41B FactSet estimate.
- Management withdrew full-year 2026 guidance amid significant Europe underperformance, an ongoing strategic review, and ahead of a leadership change with Mr. Abbate set to become President and CEO on 2026/12/15.
- Shares plunged, falling about 17% in premarket trading and dropping 20% intraday to $17.98, while Barrington Research downgraded the stock from Outperform to Market Perform with no price target after the miss.
- A securities litigation firm launched an investigation into potential misstatements about LKQ’s European operations and its ERP rollout in Germany after the profit warning, impairments, leadership exits, guidance withdrawal, and stock drop.
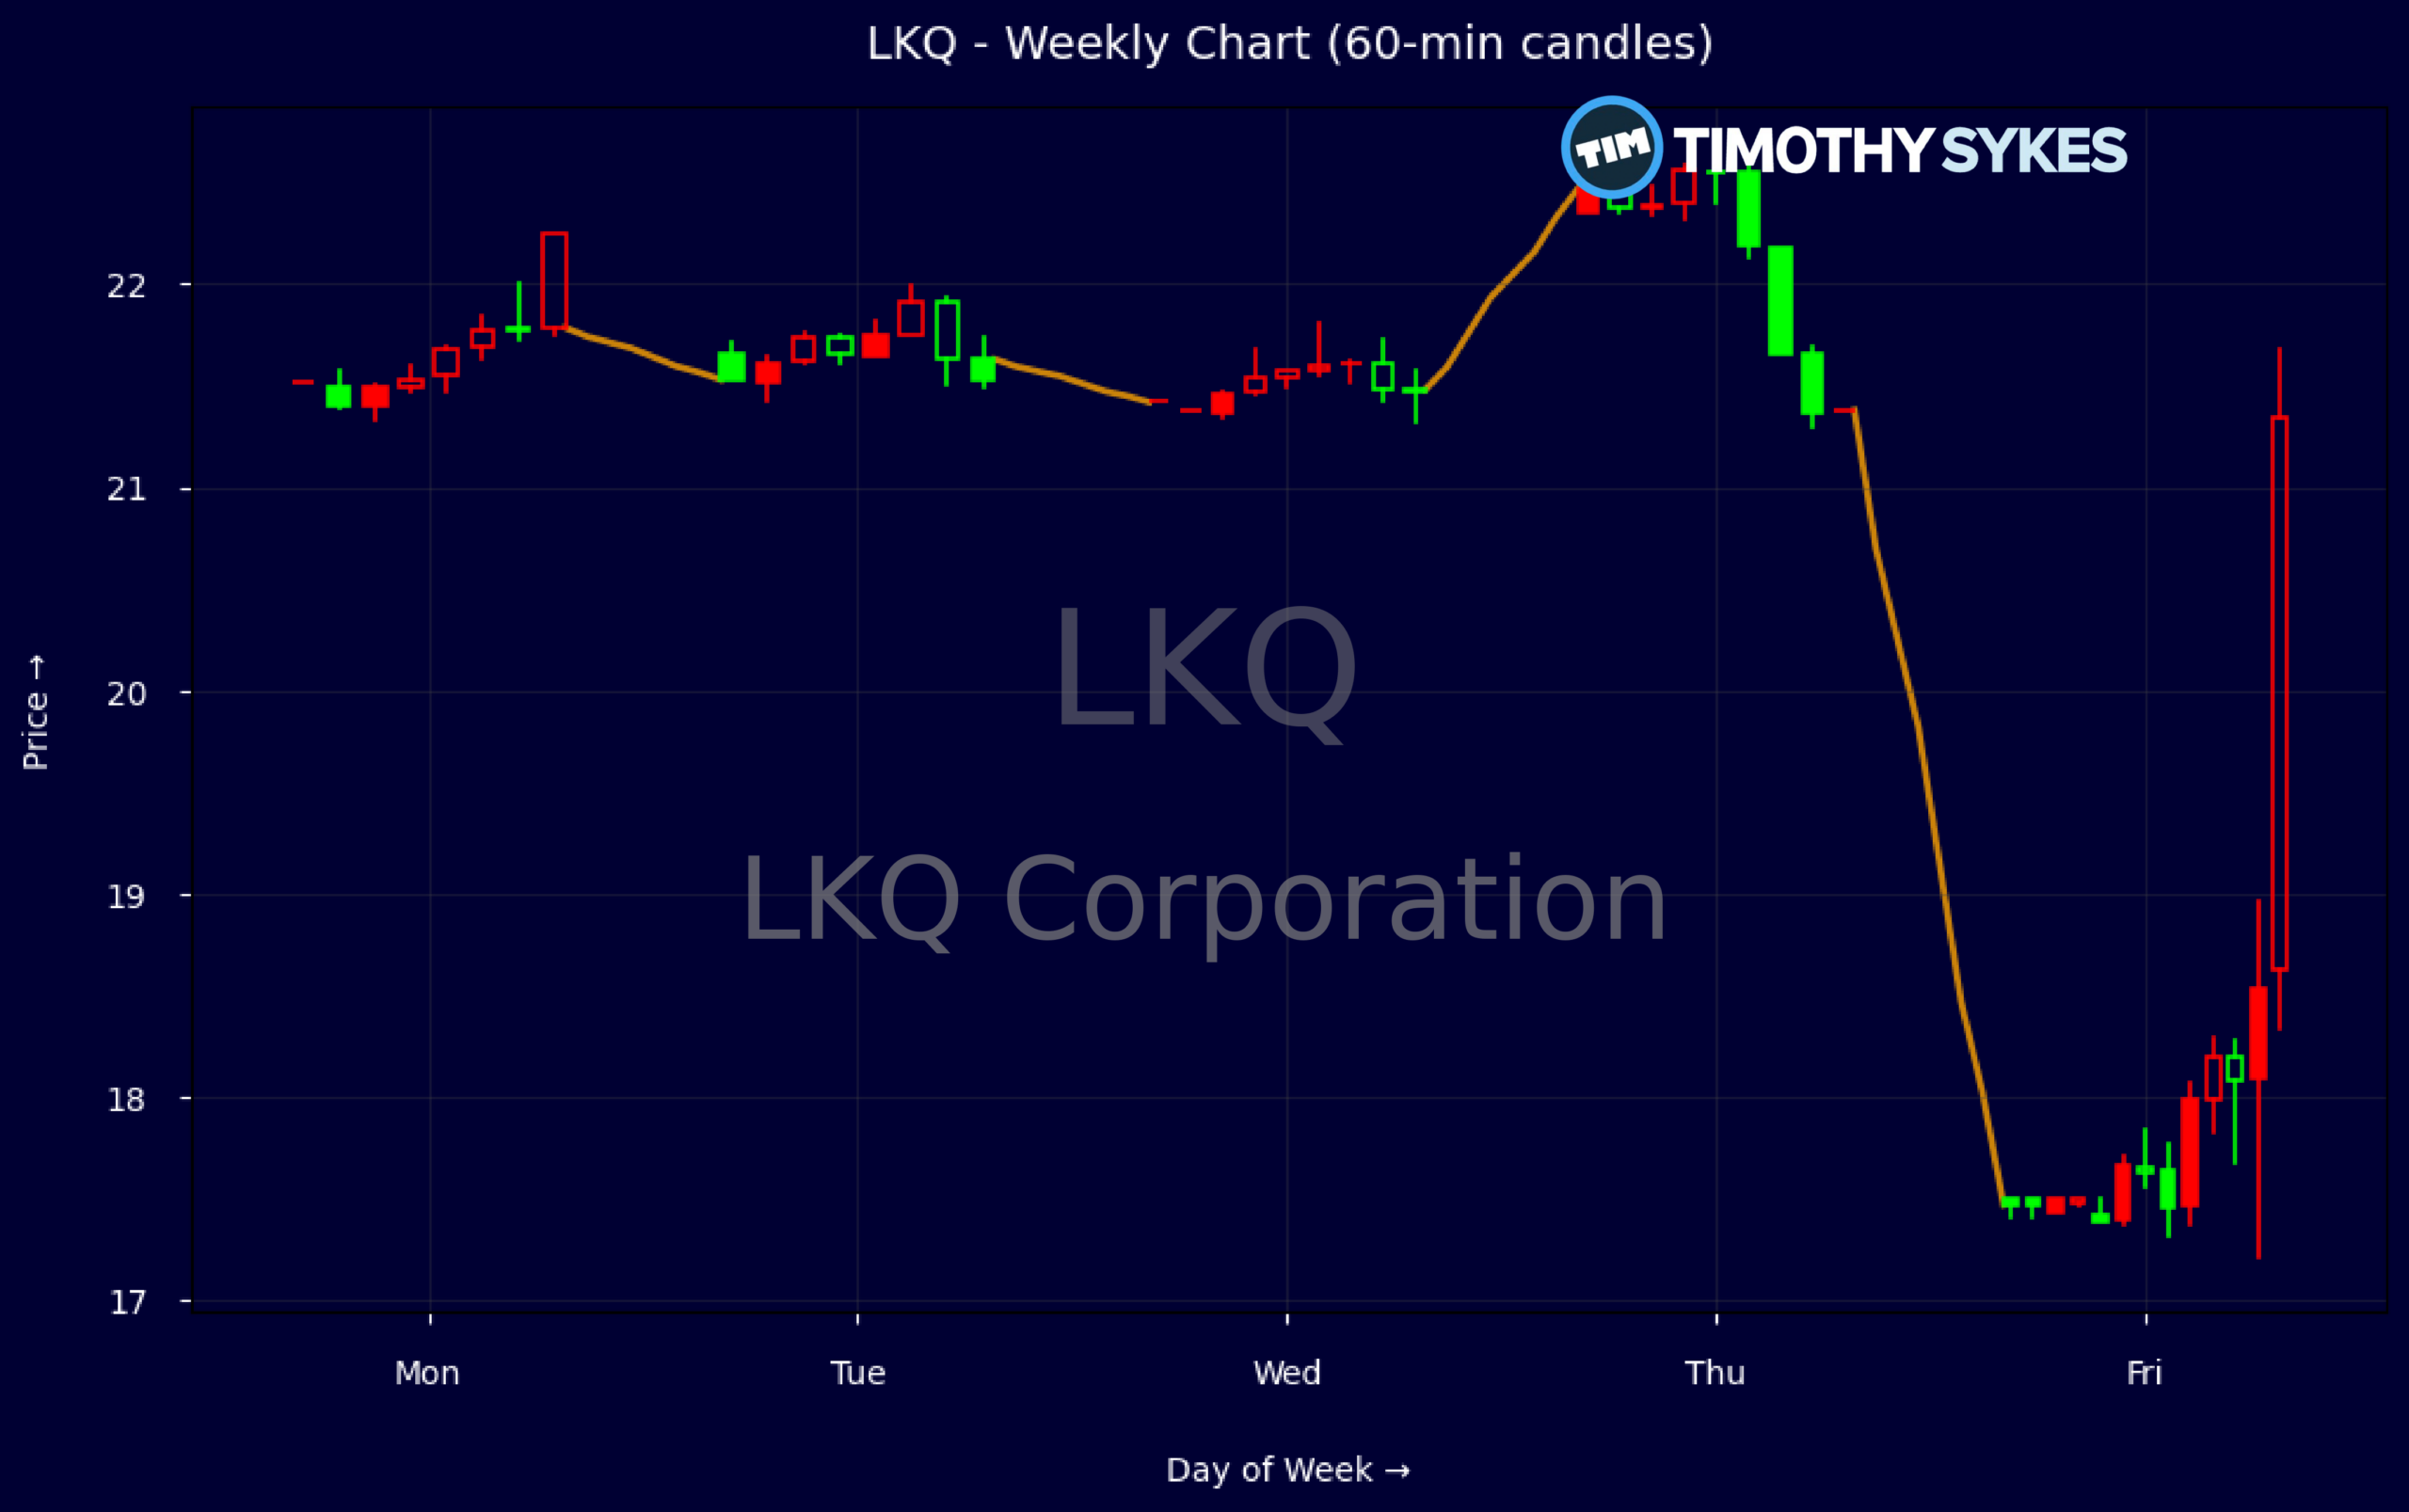
Weekly Update Oct 19 – Oct 23, 2026: On Sunday, October 25, 2026 LKQ Corporation stock [NASDAQ: LKQ] is trending down by -22.12%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Consumer Discretionary industry expert:
Analyst sentiment – negative
LKQ sits in a structurally advantaged auto-parts distribution niche but is under-earning its potential. Gross margin at 38% and pre-tax margin above 8% underscore solid unit economics, yet EBIT margin is depressed and ROE of ~9% lags historical levels. Balance sheet leverage is manageable (total debt/eq ~0.5 including leases), but interest coverage of 0.7 is a concern as rates stay high. Shares at ~0.4x sales and 0.86x book reflect a deep discount to normalized profitability and peers.
Technically, the stock has broken its prior 21.50–22.50 consolidation with an air pocket down to the high teens; the 17.39–17.50 print marks the first meaningful attempt to stabilize after a high-volume gap-down. Intraday 5-minute tape shows heavy sell volume on the open followed by short-covering, not genuine accumulation. Dominant trend is firmly down. One actionable level: 17.00 is the key line; sustained closes below it open 15.50, while failed breakdowns above 17.00 favor a tactical bounce toward 20.00.
Fundamentally and versus Consumer Discretionary and vehicle-parts benchmarks, LKQ has moved from quality compounder to turnaround. Europe is destroying value, ERP issues are self-inflicted, FY guidance is withdrawn, and a CEO transition plus investigations add governance risk. Sector peers trade on 11–14x earnings; applying a penalty multiple of 8x to trough EPS supports a 12-month fair value range of $18–20. Current risk-reward is unattractive; stance is Underweight with resistance at 20 and strong resistance at 22.
More Breaking News
Quick Financial Overview
LKQ Corporation came into this Q3 2026 shock with a solid-looking fundamental base. The latest annual data shows revenue around $13.65B, with a healthy 38.2% gross margin and profit margin near 3.4%. Valuation had been modest, with a P/E near 9.4 and price-to-sales around 0.41, signaling the market already discounted some risk before this earnings surprise.
Profitability metrics show a mixed picture. Returns on equity and assets are positive, but the EBIT margin is slightly negative, hinting at pressure from non-core charges or restructuring. Cash generation is decent, with $111M in operating cash flow and $60M in free cash flow for the latest quarter, even after $51M in capital spending and meaningful cash returned through dividends and buybacks.
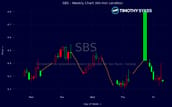
On the tape, the damage is clear. Weekly data shows LKQ sliding from the low $20s into the high teens, with the latest close near $17.50 after a violent selloff. Intraday, a 5‑minute candle with a low near $17.21 and close around $17.42 confirms heavy selling pressure and wide intraday range. Balance sheet ratios such as debt-to-equity near 0.21 and a current ratio of 1.6 offer some cushion, but the payout level implied by a roughly 6.9% dividend yield now looks aggressive if earnings stay under pressure.
Conclusion
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply