Weatherford International plc stocks have been trading up by 7.79 percent following upbeat drilling contract wins and strong earnings.
What Traders Need To Know
- Q3 EPS came in at $1.66 versus estimates around $1.27–$1.33 on revenue of $1.14B, modestly ahead of expectations.
- EBITDA margin expanded to 22.2% and adjusted free cash flow hit $155M, even with Middle East conflict disruptions.
- Year-over-year, revenue slipped from $1.23B to $1.14B while EPS rose from $1.12, signaling better profitability.
- Major banks trimmed price targets but kept Outperform/Overweight/Buy ratings, flagging Middle East and Saudi activity risks.
- The company completed the NCS Multistage deal, advanced redomestication to Delaware, cut high‑coupon debt, and locked in long-duration contracts.
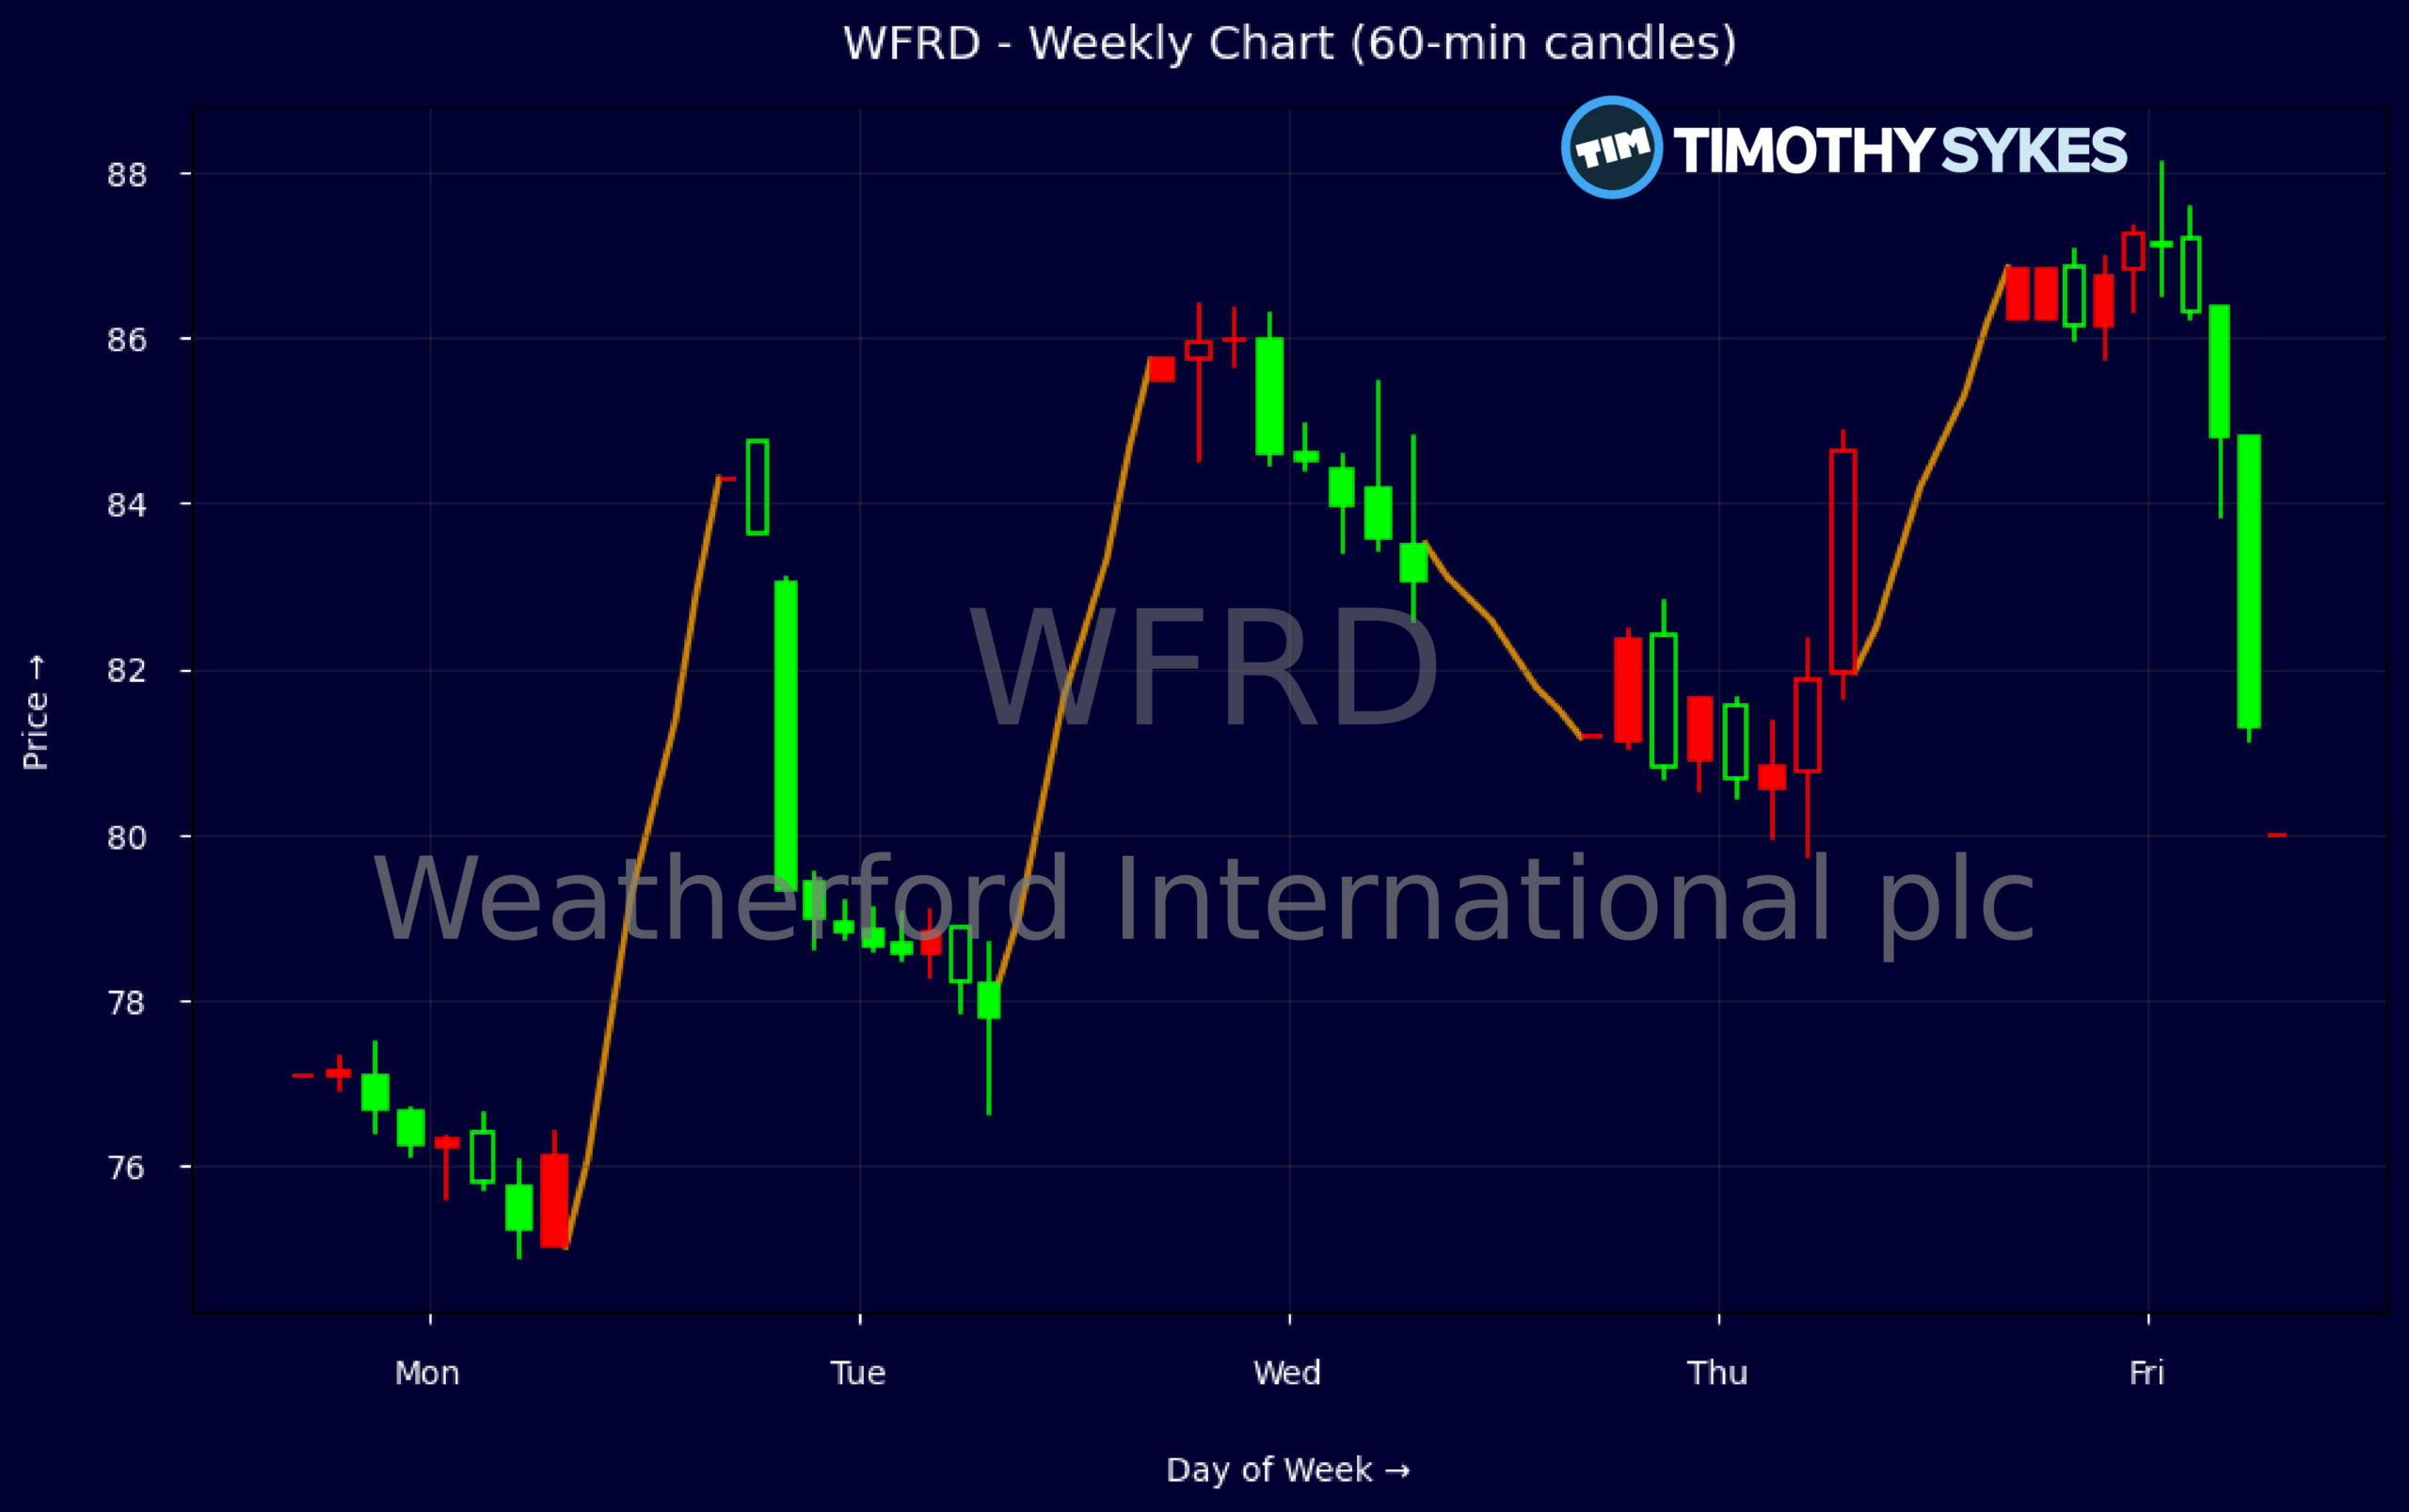
Weekly Update Oct 19 – Oct 23, 2026: On Friday, October 23, 2026 Weatherford International plc stock [NASDAQ: WFRD] is trending up by 7.79%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Energy industry expert:
Analyst sentiment – positive
Weatherford (WFRD) now occupies a top‑tier but still-discounted position within global oilfield services, with 46.7% gross margin and EBIT/EBITDA margins of 10.3%/16.2% trending higher versus the latest quarter’s ~22% EBITDA margin. ROE above 22% and ROIC mid-teens signal a structurally improved franchise, while revenue CAGR of ~7% over five years despite a recent three‑year dip shows durable recovery. Leverage is manageable (D/E 0.91, interest cover 9.5x), and FCF of $147M quarterly plus a 1.3% dividend and active buybacks underline robust capital returns.
Technically, WFRD remains in a primary uptrend despite recent volatility: the weekly sequence from ~$77 to ~$86 shows higher highs and higher lows, with buyers defending the low‑80s. Recent 5‑minute candles (not shown numerically but implied by intraday ranges and closes near highs) suggest strong demand into strength with solid volume absorption above $84. I would anchor a trading plan around $82 as first key support; above that, use dips toward $83–84 to accumulate with a tactical stop just below $80.
Fundamentally and versus Energy and Fossil Fuels benchmarks, WFRD offers superior margin expansion, higher ROE, and faster FCF accretion than most diversified service peers, reflected in widespread Buy/Overweight ratings and a consensus target near $114, well above the mid‑$80s spot. Middle East disruptions cap near‑term growth, but contract wins, the NCS Multistage integration, and balance sheet de‑risking support multiple expansion. I see upside toward $105–115 over 12–18 months, with support at $80 and resistance near $95.
More Breaking News
Quick Financial Overview
Weatherford International plc just printed the kind of quarter that gets short-term traders’ attention. Q3 2026 revenue was $1.143B, slightly ahead of consensus, but the real story was earnings power: EPS landed at $1.66 with EBITDA of $214M and an EBITDA margin of 22.2%. That is a sharp step up from the longer-term EBITDA margin profile around the mid-teens, tying directly to better cost control and mix. Net income of $120M on $1.143B of sales lines up with profit margins in the high‑single digits, consistent with the 7.7–8.0% range in the ratio set.
The balance sheet and cash flows back that strength. Weatherford International plc generated $192M of operating cash flow and $147M of free cash flow in the quarter, matching the news figure of $155M adjusted free cash flow. With enterprise value near $6.35B against trailing revenue of about $4.918B, WFRD trades around 1.2x sales and roughly 9–10x free cash flow, supported by a current ratio of 2.3 and interest coverage of 9.5. Debt-to-equity of 0.91 and long‑term debt of about $1.319B look manageable given $1.161B of cash.
On the tape, WFRD has been in a firm short-term uptrend. Weekly closes climbed from $77.09 to $86.25 over the last data points, and intraday action shows a steady grind higher from the $82–$83 zone at the open to a late-day push into the mid‑$86s. The 5‑minute chart is classic trend day behavior: higher lows, contained pullbacks, and no real breakdown under prior support. With a recent share price cited near $82.35 against a mean analyst target around $114.09, the Street is still implying sizable upside, even after RBC, Barclays, Citi, UBS, Piper Sandler, and Goldman all nudged targets lower in response to Middle East and Saudi uncertainty.
Conclusion
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply