LKQ Corporation faces heightened pressure as its stocks have been trading down by -22.12 percent following negative earnings-related sentiment.
What Traders Need To Know
- Q3 2026 was pre-announced as weak, with Europe seeing nearly a 10% organic revenue drop, sharp margin compression, and large impairments that flipped continuing operations into a net loss.
- Preliminary Q3 adjusted EPS of $0.47–$0.53 versus $0.69 consensus and revenue of about $3.32B versus $3.41B estimates mark a clear reset in earnings power.
- Management linked the European shortfall to ERP rollout issues in Germany and softer volumes in the UK and Benelux, while North America held in line and Specialty only slightly missed.
- Full-year 2026 guidance was withdrawn, a CEO change takes effect on 2026/12/15, and Alvarez & Marsal was hired to stabilize Europe under an ongoing strategic review.
- A sharp selloff took shares down about 17% premarket and roughly 20% intraday to $17.98, following a downgrade to Market Perform and a securities litigation probe into potential misstatements on the European business.
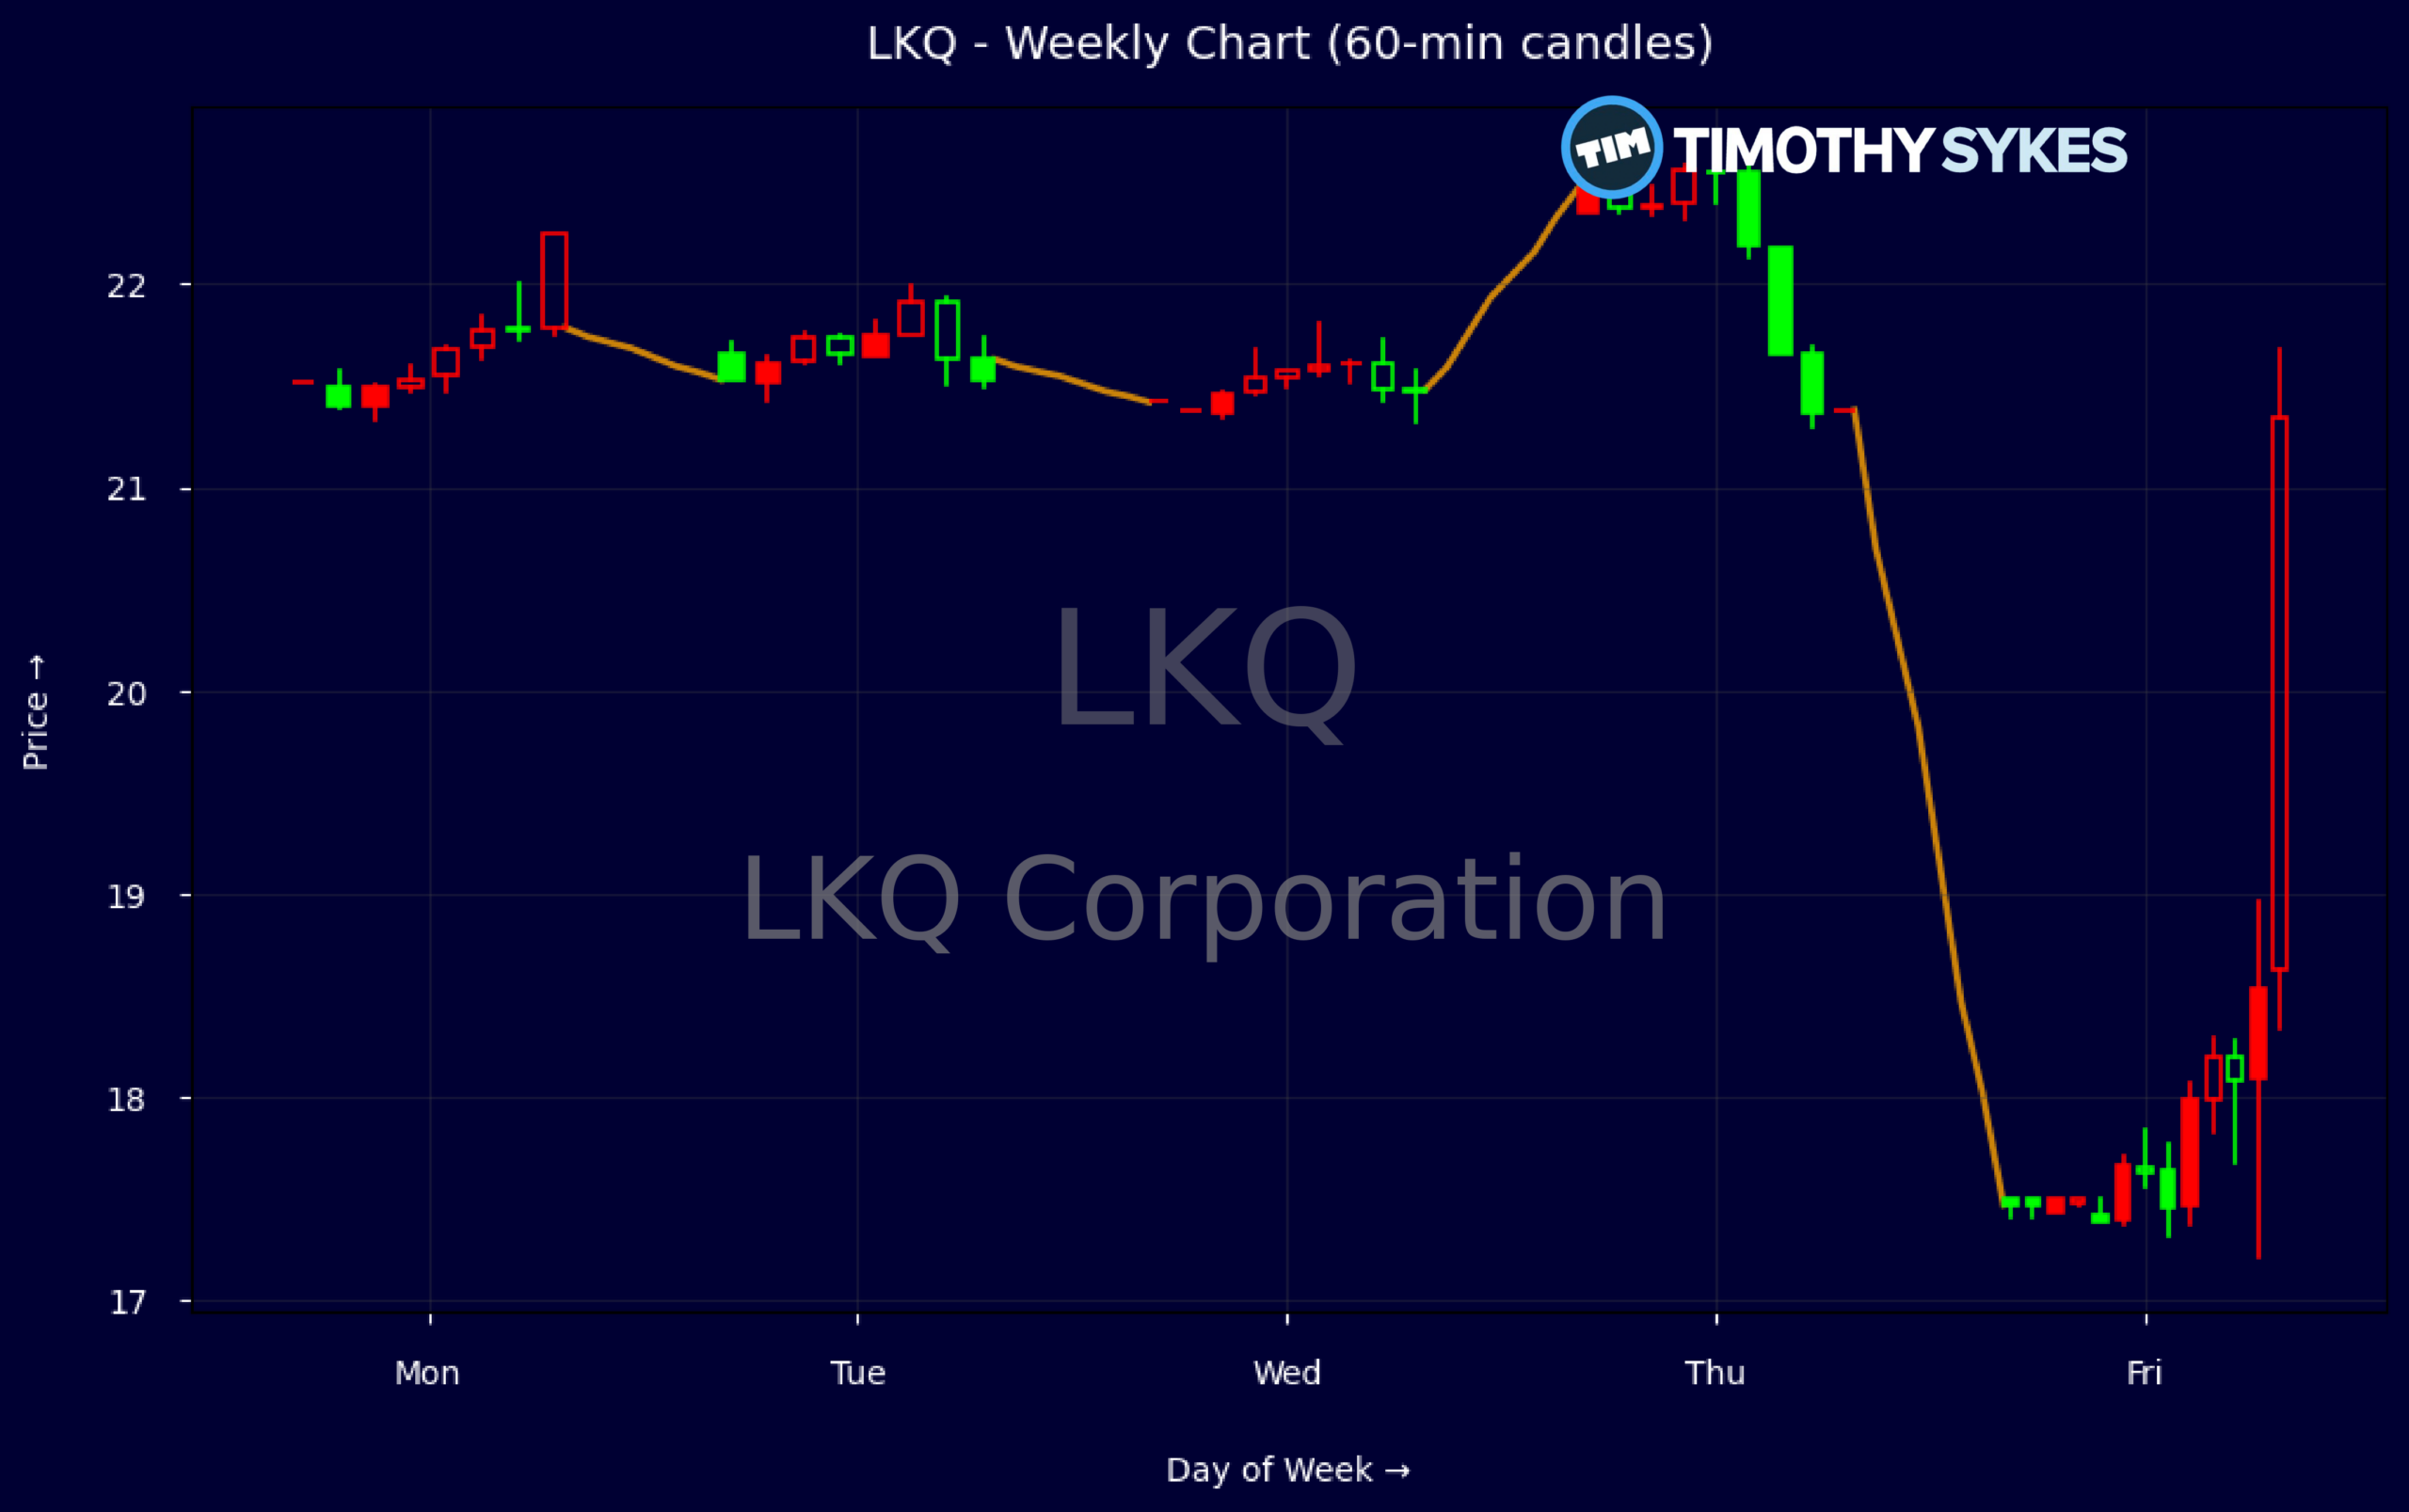
Weekly Update Oct 19 – Oct 23, 2026: On Saturday, October 24, 2026 LKQ Corporation stock [NASDAQ: LKQ] is trending down by -22.12%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Consumer Discretionary industry expert:
Analyst sentiment – negative
LKQ remains a scaled, essential player in aftermarket and recycled auto parts, but fundamentals are deteriorating. Gross margin at 38% is healthy, yet EBIT margin is slightly negative and EBITDA margin just 2.8%, reflecting European execution issues and non‑recurring charges. Despite 1.3% three‑ and five‑year revenue CAGRs, returns are mediocre (ROE ~7–9%, ROA ~3–4%). Valuation screens optically cheap at ~9.4x P/E and 0.41x sales, but weak interest coverage (0.7x) flags elevated risk.
Technically, the dominant trend is sharply bearish. The stock broke from the 21–22.5 consolidation zone to 17.4–17.5 on a single high‑volume washout session, confirming a downside momentum break and likely forced/institutional de‑risking. Intraday 5‑minute candles show heavy selling on upticks and failed bounces, indicating supply at every rally. The first actionable level is resistance at ~21.50; tactically, I would avoid longs below 18 and use 21.50 as a fade level for short‑term trades.
Near term, the setup is decisively negative. The Q3 pre‑announcement (EPS guide 0.47–0.53 vs. 0.69 cons, revenue light, Europe down ~10% organically) plus guidance withdrawal, CEO transition, and a restructuring advisor in Europe place LKQ well behind Consumer Discretionary and Vehicles peers on growth, visibility, and governance. The downgrade and potential securities litigation add overhang. I see fair value compressed toward 16–18, with resistance at 21–22; risk‑reward is unfavorable.
More Breaking News
Quick Financial Overview
LKQ Corporation comes into this selloff with a mixed financial base. On the positive side, trailing revenue is about $13.65B with a solid 38.2% gross margin, showing the core model can generate healthy markups on parts and services. Net margin from continuing operations sits near 3.44%, which is thin but workable for a scaled distributor when execution is clean.
Leverage is moderate, with total debt to equity at 0.21 and a current ratio around 1.6, suggesting the balance sheet is not the main problem. However, interest coverage of only 0.7 and an EBIT margin near -0.3% flag how fast earnings power has deteriorated. A price-to-earnings ratio around 9.4 and price-to-sales near 0.41 now reflect the market’s discount for execution risk and Europe-driven uncertainty.
On the cash flow side, recent quarterly operating cash flow of $111M and free cash flow of $60M support an annual dividend of $1.20, implying a high yield near 6.9% at current prices. The latest weekly candle shows LKQ plunging from above $22 to the $17–$18 zone, a roughly 20% reset that matches the news shock. Intraday, the 5-minute data highlight a gap-down open around $18.16 with a spike to $18.29, then a drive down toward $17.21 and a weak bounce to about $17.42, signaling heavy distribution and no clear intraday support yet.
Conclusion
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply