
Amazon.com Inc. stocks have been trading up by 3.71 percent amid strong e-commerce growth and robust cloud demand optimism.
Key Takeaways
- Record Q3 2026 operating margin of 13.9% on $201.9B in sales shows AMZN turning scale into serious profit, with AWS running at roughly $184B and ~39% margin.
- AWS growth re-accelerated to 39.3% year over year for the sixth straight quarter, backed by a $578B backlog and heavy AI infrastructure capex.
- Management says AWS capacity for 2026 is sold out and most of 2027 is already booked, justifying about $220B of capex focused on data centers and networking.
- UBS and Freedom Broker lifted AMZN price targets to $352 and $330, flagging a multi‑year AWS acceleration and potential AWS revenue growth above 40% in 2027–2028.
- Bedrock and Amazon’s custom Graviton and Trainium chips are scaling fast, with silicon commitments up more than 20x and over $2B in customer savings in Q3.
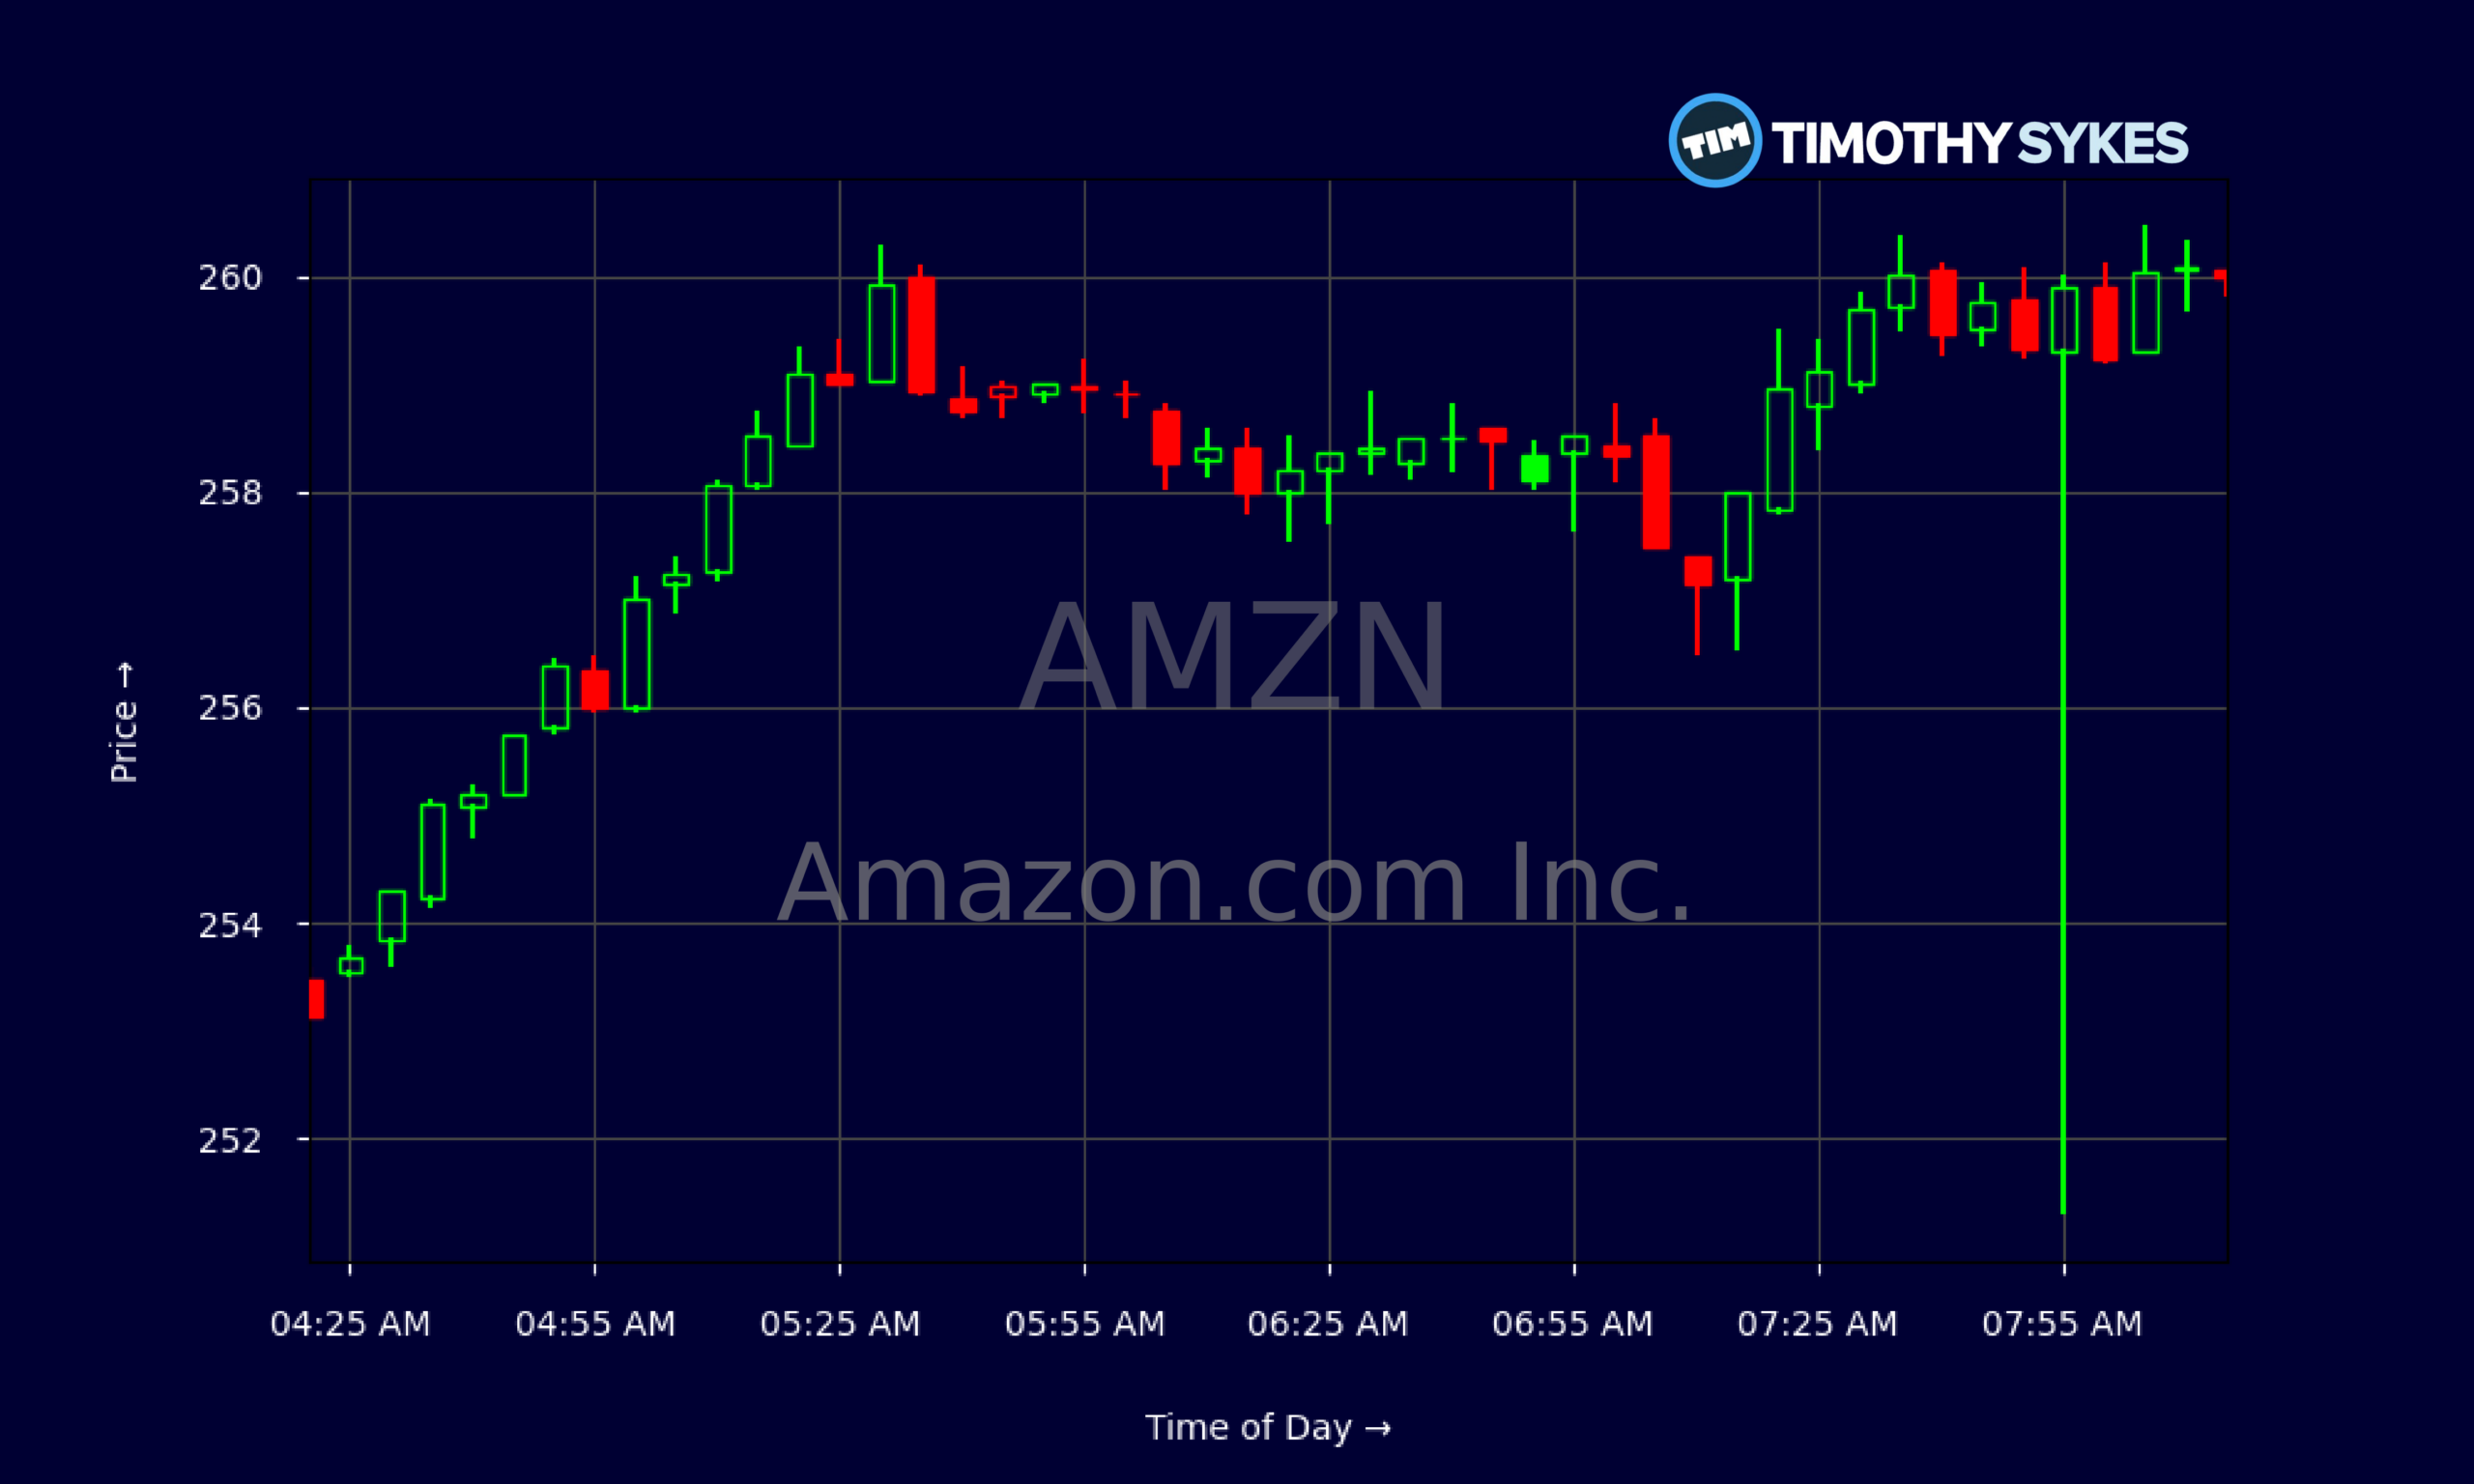
Live Update At 08:18:51 EST: On Wednesday, November 04, 2026 Amazon.com Inc. stock [NASDAQ: AMZN] is trending up by 3.71%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
AMZN’s tape reflects a strong uptrend that has paused but not broken. Over the past few weeks, the stock pushed from the low $250s toward $265 before pulling back, with recent closes clustering around $245–$255. That tells traders AMZN is consolidating after a strong leg higher, not collapsing. Average daily ranges of roughly $5–$10 show healthy volatility for active trading without pure chaos.
Intraday data paints the same picture. Pre‑market prints around $258–$260 with tight 5‑minute candles show steady two‑sided action and liquidity. There is no sign of a panic gap or air pocket; AMZN is trading like a big liquid leader that funds lean on for AI and megacap exposure.
More Breaking News
Under the hood, Amazon.com Inc. just backed that chart with serious fundamentals. Trailing revenue sits around $716.9B, with a gross margin of 50.8% and an EBIT margin near 23%. A P/E around 21 and price‑to‑sales of 3.65 are not cheap in absolute terms, but for a platform posting double‑digit revenue growth and a 30%+ return on equity, traders often accept a premium. Low debt (total debt‑to‑equity of 0.23) and interest coverage above 76 give AMZN plenty of room to keep pressing its AI and cloud advantage.
Why Traders Are Watching AMZN’s AI Supercycle
For active traders, AMZN is no longer just an e‑commerce story; it is an AI infrastructure leader with visible demand stretching years out. In Q3 2026, Amazon.com Inc. delivered $201.9B in sales, up 12% year over year, and hit a record 13.9% operating margin. That kind of profitability at this size is rare. The engine is AWS, which grew 39% year over year, driving to a roughly $184B run‑rate and about 39% margin.
AMZN also reported AWS net sales of $45.98B, up from $33.0B a year earlier, with operating income jumping to $17.77B from $11.43B. For traders, that means the cloud segment is becoming the clear profit center, capable of offsetting weaker spots in lower‑margin retail when macro conditions wobble.
The real hook is forward visibility. Management says AWS growth has re‑accelerated to 39.3% year over year for the sixth straight quarter and is backed by a $578B backlog. CEO Andy Jassy added that AWS capacity for 2026 is sold out, 2027 is largely booked, and a meaningful slice of 2028 is already spoken for. AMZN plans about $220B in 2026 capex, mostly data centers, servers, networking, and its Bedrock AI platform. Free cash flow is negative now, but those pre‑sold contracts show why the company is stepping on the gas.
On top of that, Amazon Bedrock is exploding. Fortune 500 spending is up nearly 7x, token volume roughly 17x, and Bedrock is already the fastest‑growing multi‑billion‑dollar service in AWS history. Custom silicon — Graviton CPUs and Trainium accelerators — is growing triple digits, with revenue commitments up more than 20x and over $2B in customer savings in Q3 alone. For AMZN traders, these are the kind of second‑ and third‑layer growth drivers that can keep the story hot well beyond a single earnings print.
Wall Street is taking note. UBS bumped its AMZN price target to $352, and Freedom Broker raised its target from $255 to $330, both highlighting expectations for AWS revenue growth above 40% in 2027–2028 and even talking about AWS as a potential $1T business over time. When big firms lean this bullish, dips often turn into liquidity for funds rather than trend reversals.
Conclusion
AMZN is doing what seasoned traders want to see from a large‑cap leader in an AI supercycle: posting record margins today, while aggressively funding tomorrow. Q3 brought 12% revenue growth, a 13.9% operating margin, and AWS growing 39% with hefty 39% margins. At the same time, Amazon.com Inc. is spending around $220B on capex in 2026, driving free cash flow negative but lining up years of contracted cloud and AI demand.
That trade‑off is central to the AMZN setup. You have a $578B AWS backlog, sold‑out capacity for 2026, and strong bookings into 2027 and 2028. You also have high‑growth layers like Bedrock and in‑house silicon, plus expanding retail plays in grocery and other verticals. Analysts lifting price targets into the $330–$352 zone are essentially saying they are willing to look through near‑term cash burn because the growth runway looks long and clear.
For short‑term traders, that often translates to buying support zones and respecting breakouts rather than blindly fading strength, while keeping risk tight because any stumble in AWS or AI demand would hit sentiment fast. In that kind of fast‑moving environment, discipline and timing matter more than constant activity; as millionaire penny stock trader and teacher Tim Sykes says, “Be patient, don’t force trades, and let the perfect setups come to you.”. Or, as Tim Sykes likes to remind his community, “The market rewards preparation, not prediction — have your trading plan ready before the move, or you’ll end up chasing it.” This article is for educational and research purposes only and is not investment advice.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:

Leave a reply