Transocean Ltd (Switzerland) stocks have been trading up by 5.96 percent following bullish offshore drilling contract and backlog news
Key Takeaways Traders Need On RIG Now
- Transocean added roughly $1.1B to firm backlog, anchored by a new ~$62M, 120‑day two‑well Norge contract with A/S Norske Shell in Norway and final Equinor approval on a ~$1.0B multi‑rig deal.
- Brazil’s competition authority granted unconditional approval for Transocean’s planned Valaris acquisition, clearing regulatory risk and lining up a Q4 closing.
- The company extended and upsized its main revolving credit facility to $750M, moving maturity to 2031 and tying it to the Valaris transaction.
- Management fully redeemed $165M of 8% Aquila Notes, trimming future interest expense by about $22M and showing steady balance sheet cleanup.
- RIG traded about 0.7% higher pre‑market on the Norge contract news, a positive move despite softer energy benchmarks.
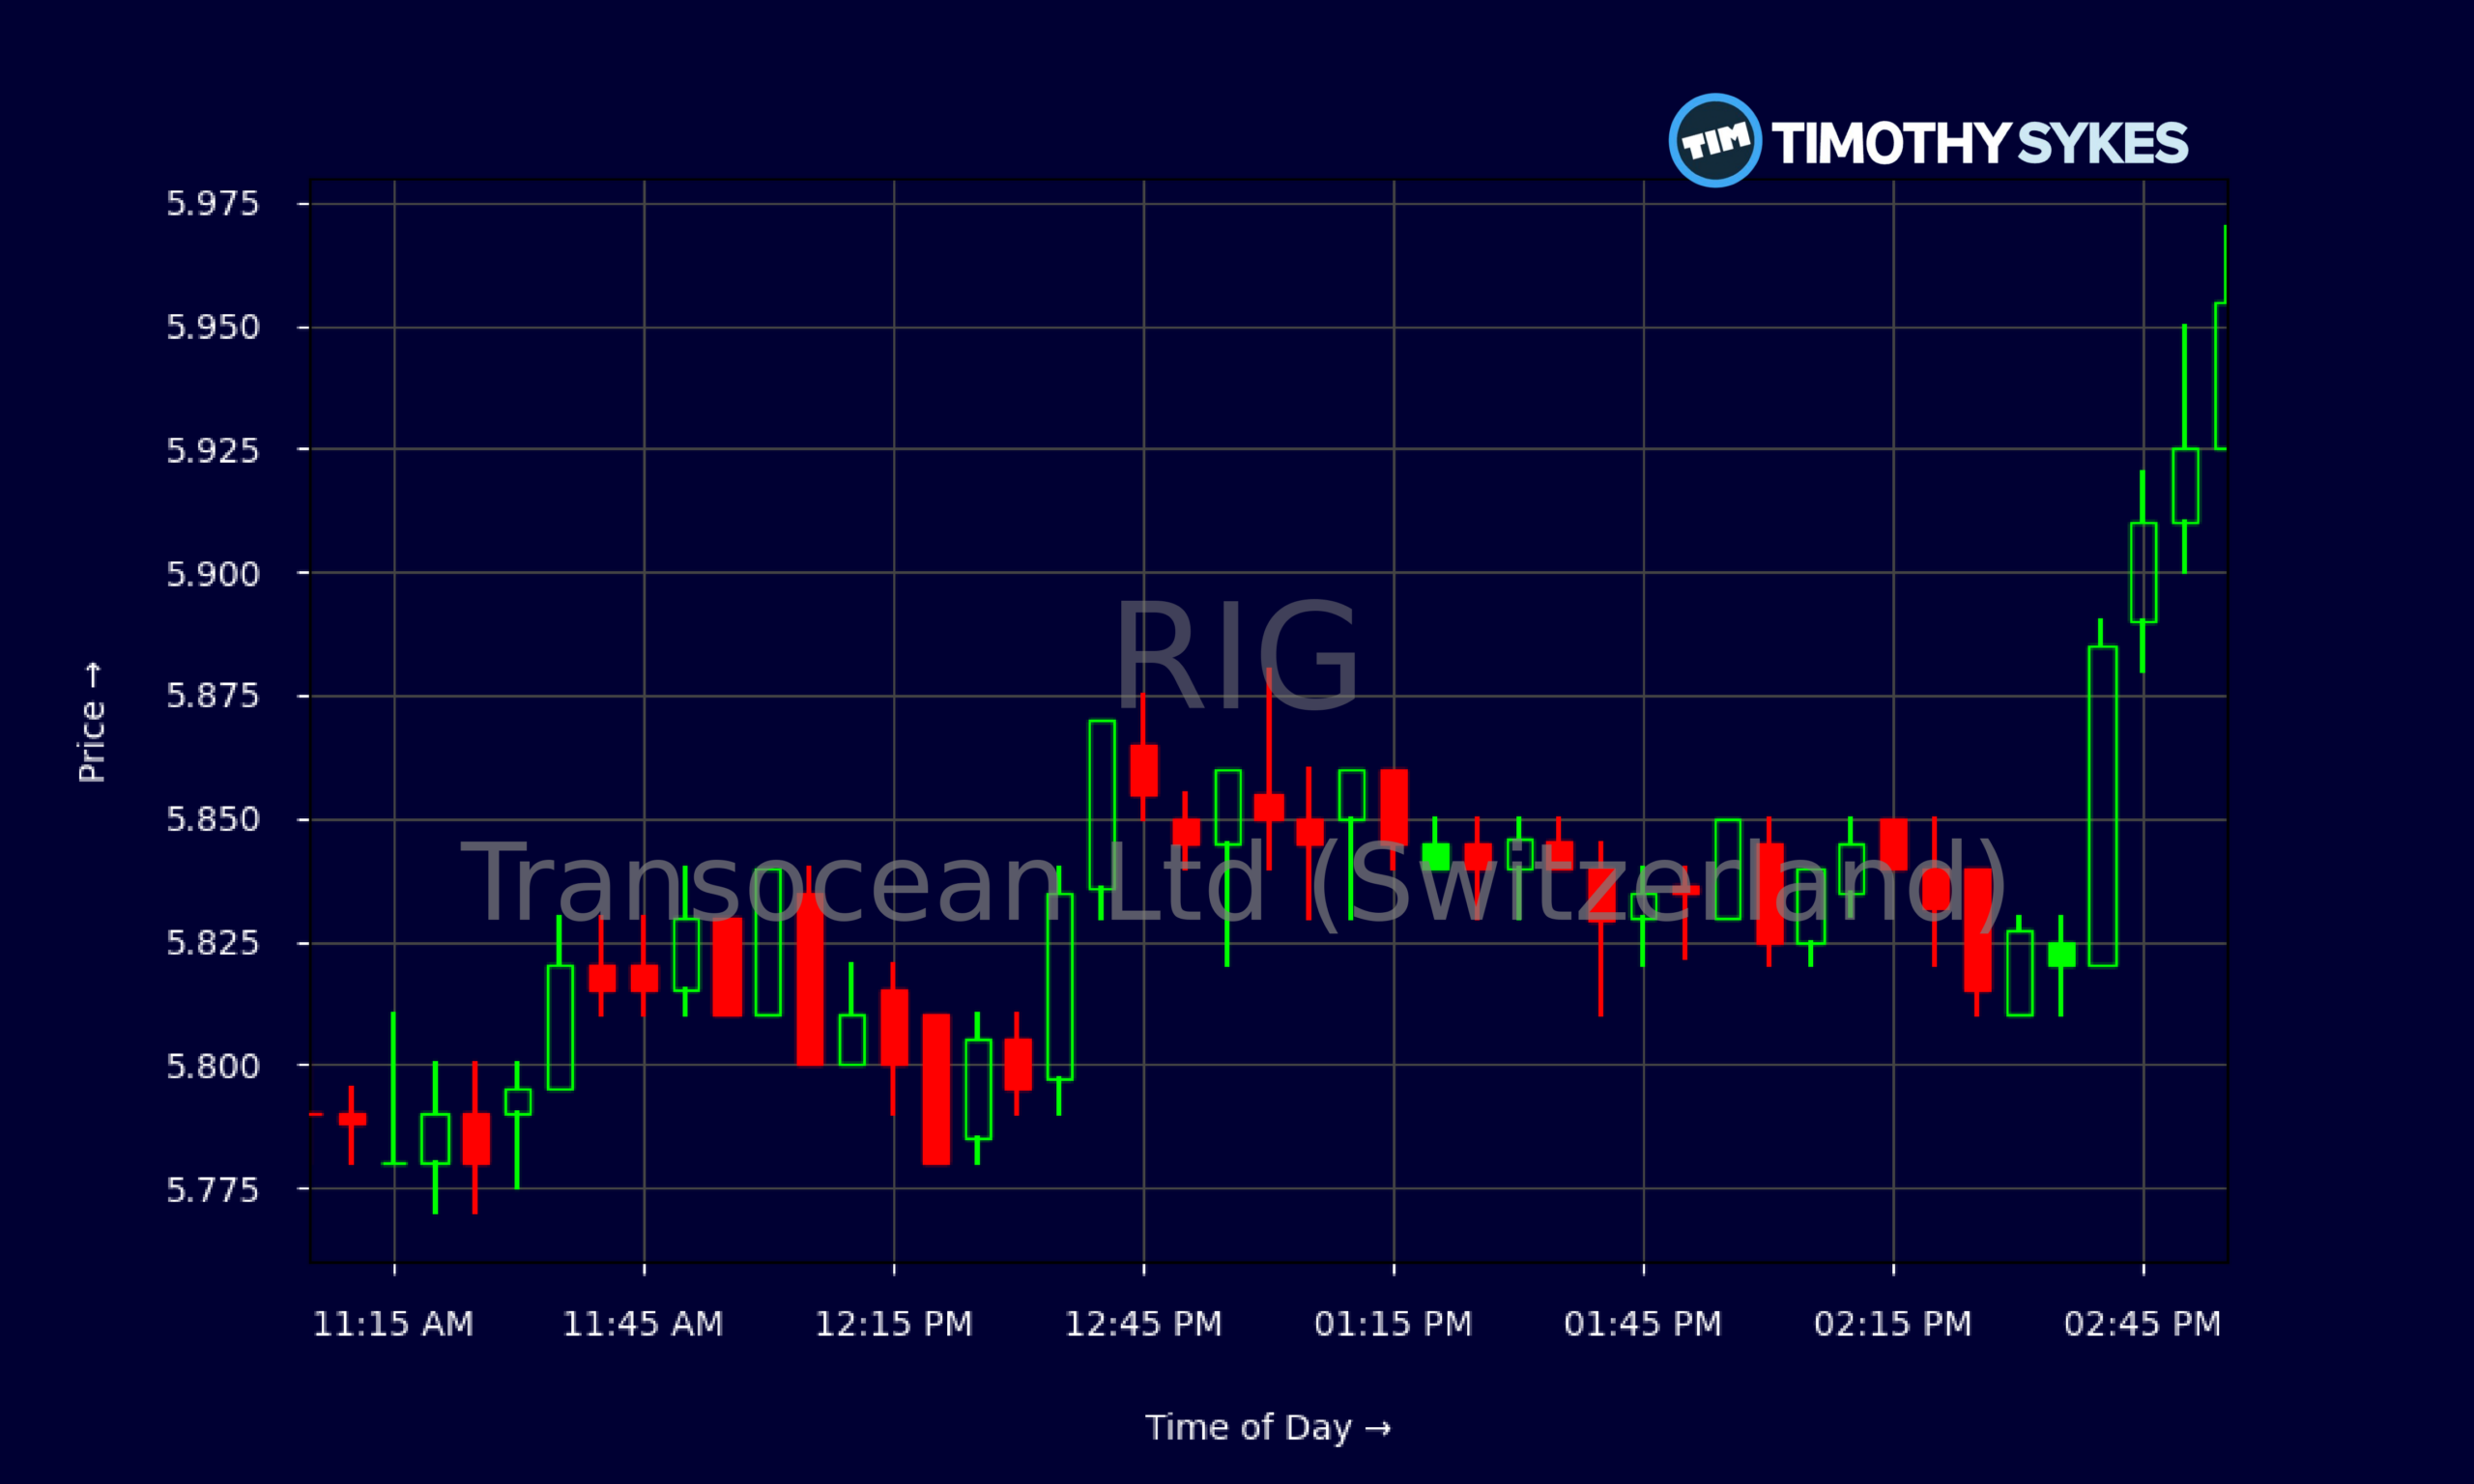
Live Update At 15:02:51 EDT: On Monday, October 19, 2026 Transocean Ltd (Switzerland) stock [NYSE: RIG] is trending up by 5.96%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
Transocean Ltd (Switzerland), trading as RIG, is acting like a classic turnaround name with improving fundamentals. The daily chart shows a steady grind higher: from around $5.17 on 2026/10/02 to about $5.96 on 2026/10/19. That’s a solid near‑15% run in just over two weeks, with dips consistently bought and closes near the top of the daily ranges.
Intraday action on the latest session backs that up. RIG opened around $5.72, tested down briefly, then pushed toward $5.97 into the close. The tape shows tight five‑minute candles and higher lows most of the afternoon, typical of controlled accumulation rather than wild speculation.
Under the hood, RIG’s fundamentals are shifting. Revenue sits near $3.97B with positive recent growth, but margins over the last year still screen negative. Profitability ratios like return on equity and return on assets are in the red, reflecting past pain. However, the latest quarterly data shows $170M in net income and $236M in operating cash flow, plus about $212M in free cash flow.
More Breaking News
Valuation remains undemanding: price‑to‑sales around 1.5 and price‑to‑book roughly 0.74, with no active dividend. Debt is meaningful but not extreme, with total debt‑to‑equity about 0.61 and a current ratio of 1.6. For traders, that mix — low book multiple, improving cash flow, tightening chart — often sets up strong momentum swings when sentiment turns.
Why Traders Are Watching RIG’s Backlog And Valaris Deal
The real driver for RIG right now is contracting and scale. Transocean just locked in about $1.1B of fresh firm backlog. That includes a new ~$62M, 120‑day two‑well deal for the Transocean Norge rig with A/S Norske Shell in Norway, plus final approval that flips a previously announced ~$1.0B multi‑rig Equinor agreement into hard, signed backlog. For an offshore driller, backlog is lifeblood — it’s forward revenue visibility that can bridge through commodity swings.
RIG’s harsh‑environment rigs are some of the most sought‑after assets in Norway. Seeing Shell and Equinor double down tells traders demand and pricing power in that niche are holding up. That’s why a relatively small $62M contract still nudged RIG up around 0.7% pre‑market on 2026/10/09, even while broader energy names and crude prices traded softer. The market is rewarding each incremental backlog win.
At the same time, RIG is pushing a transformational acquisition: Valaris. Brazil’s competition authority has now cleared the Valaris–Transocean business combination without restrictions. With this unconditional antitrust approval, all regulatory conditions are essentially satisfied, lining the merger up to close in Q4 2026.
Scale matters in this space. Combining RIG and Valaris would knit together two large offshore fleets, improve utilization optionality, and strengthen negotiating leverage with majors like Shell and Equinor. Traders are starting to shift focus from “Will this close?” to “How big are the synergies and what happens to earnings power once dayrates filter through?”
To backstop this strategy, Transocean amended and restated its main credit facility. The revolver is now $750M, extended from 2028 out to 2031, and was oversubscribed — a strong signal that banks believe in the combined RIG–Valaris story. The facility is contingent on the Valaris deal closing, tying financing directly to the bigger platform.
On top of that, RIG redeemed $165M of 8% Aquila Notes, chopping roughly $22M from future interest expense. This is basic but powerful: less interest drag means more room for earnings leverage when dayrates and utilization move higher. For traders focused on downside risk, a longer‑dated revolver and lower coupon costs both cut the tail risk that scared people in earlier downturns.
Conclusion
For active traders, RIG now sits at an interesting crossroads of improving operations, cleaner financing, and a near‑term catalyst calendar. The stock has already bounced from the low‑$5s into the high‑$5s, supported by firm tape and rising volume. Backlog has jumped by about $1.1B thanks to the Norge contract and the now‑firm Equinor deal, giving Transocean Ltd (Switzerland) clearer revenue visibility into the back half of the decade.
The Valaris acquisition is the other major piece. With Brazilian antitrust authorities granting unconditional approval, regulatory risk has largely faded. The amended $750M revolver, extended to 2031 and tied to the merger, tells you lenders are comfortable financing a bigger, more leveraged offshore player as long as the combined entity keeps generating cash. Add in the $165M of 8% notes retired and RIG’s capital structure looks less fragile than in past cycles.
Traders also have a defined near‑term checkpoint. Transocean has already set the date for its Q3 2026 earnings release and fleet status update. That call should cover backlog trends, Valaris closing timing, and further debt actions — all key for short‑term trading plans around RIG.
Tim Sykes likes to remind traders, “You don’t have to trade every stock — you trade the ones with the best risk‑reward and the clearest catalyst.” As millionaire penny stock trader and teacher Tim Sykes, says, “Consistency is key in trading; don’t let emotions dictate your trades.” Right now, RIG is building a case on both fronts: tightening charts, rising backlog, and a pending merger that the market will keep repricing as new data hits.
This article is for educational and research purposes only and is not investment advice.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply