Seadrill Limited stocks have been trading up by 7.75 percent following upbeat offshore drilling contract and utilization news.
What Traders Need To Know
- Seadrill secured an approximately $420M, ~880‑day drillship contract for West Carina in Indonesia, with up to 880 additional option days.
- The company extended the West Capella’s work in Malaysia through February 2028, adding about $94M in backlog plus potential upside from unpriced options.
- Through its 50:50 joint venture, Seadrill locked in a roughly three‑year extension for the drillship Sonangol Libongos in Angola, fully committing it through January 2030.
- The company also won a short 25‑day contract for Sevan Louisiana in the U.S. Gulf of Mexico starting in November 2026.
- Management stated that all three legacy drillship contracts are repriced to higher dayrates and over 85% of 2027 drillship days are contracted, strengthening revenue visibility.
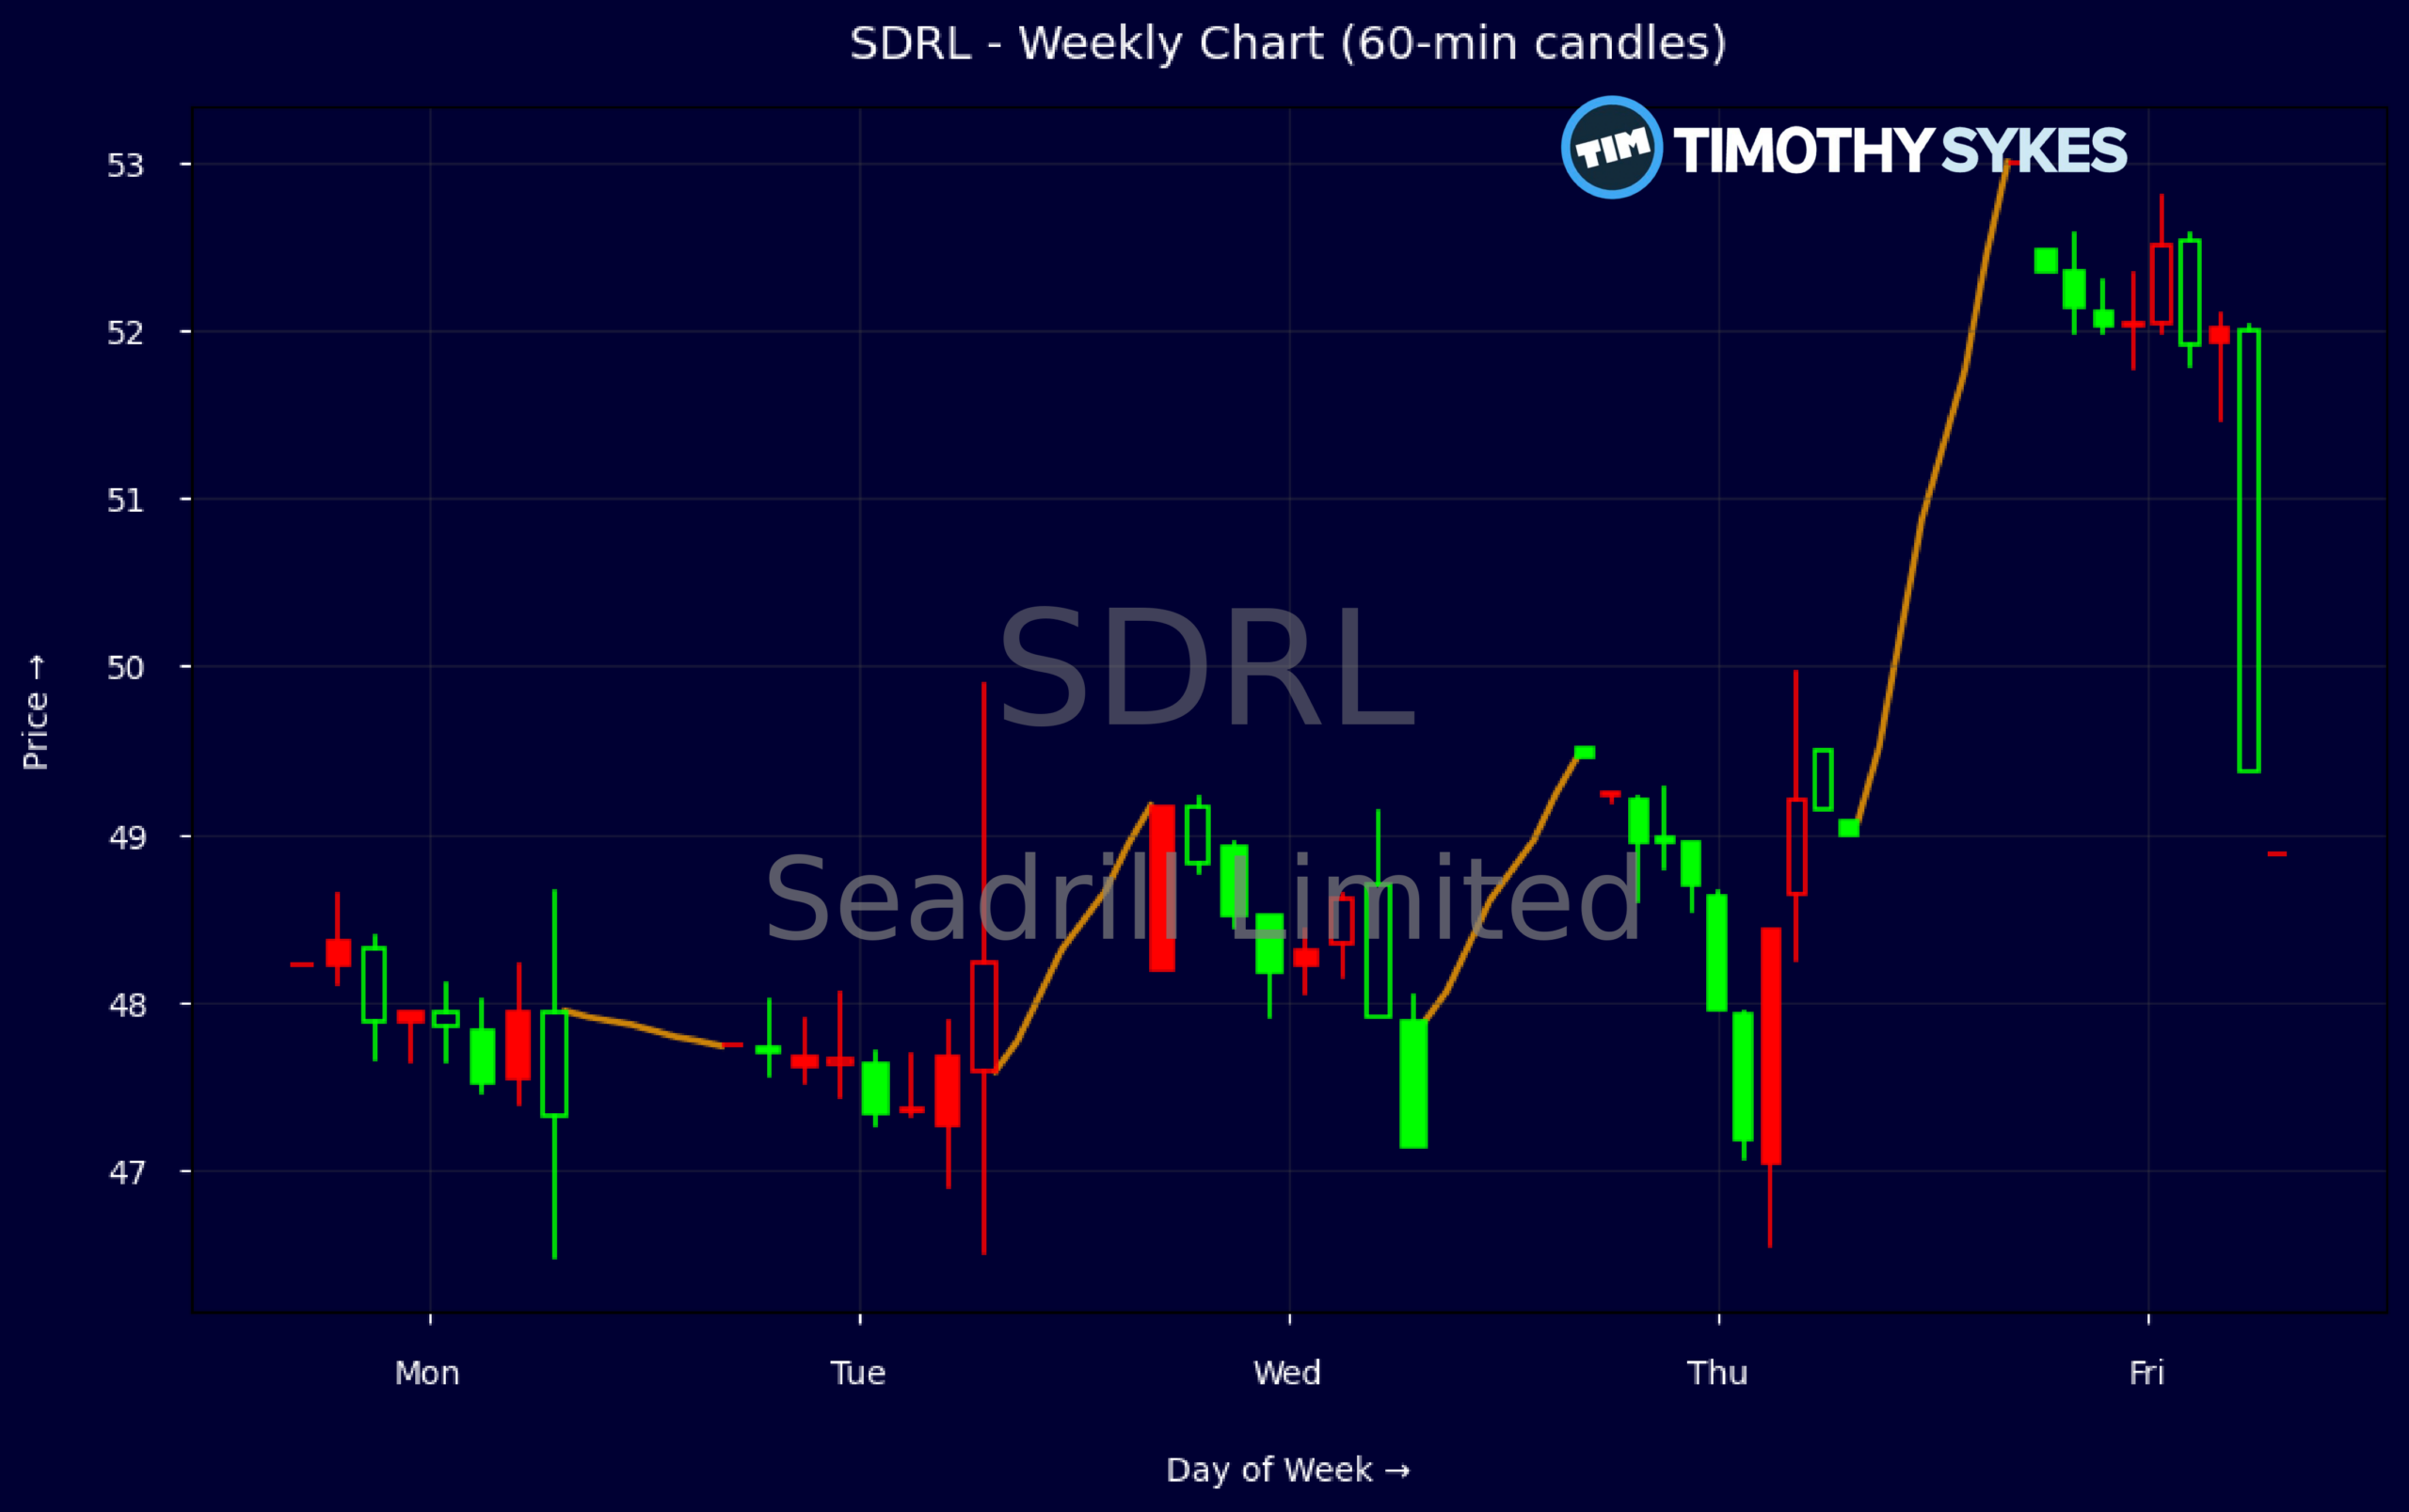
Weekly Update Oct 19 – Oct 23, 2026: On Saturday, October 24, 2026 Seadrill Limited stock [NYSE: SDRL] is trending up by 7.75%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Energy industry expert:
Analyst sentiment – positive
Seadrill stands as a recovering but still operationally mixed offshore driller, with strong revenue momentum but uneven profitability. Revenue growth (three-year +88.7%, five-year +27.7%) and a solid EBITDA margin of 27.7% support its competitive position as deepwater dayrates reset higher, yet EBIT margin of 9.9% and negative pretax margin highlight residual cost and interest drag. Balance sheet strength is a clear positive: net leverage is modest (total debt-to-equity 0.26, current ratio 2.5, quick ratio 1.8), giving Seadrill flexibility to ride the upcycle despite currently negative operating cash flow and free cash flow in the latest quarter.
Technically, the stock has broken out from the high‑40s consolidation into the low‑50s, with the weekly sequence from 47–49 to a 53 close confirming a short‑term bullish trend and strong demand absorption. Intraday 5‑minute action shows consistent buying into strength rather than gap‑and‑fade behavior, with rising volume on up‑moves, validating the breakout. A key actionable level is $49.50–$50.00 as first support; above that, momentum buyers can stay long, while a decisive break back below $48 would invalidate the immediate upside setup and suggest a return to range trading.
Fundamentally, new multi‑year contracts and extensions across West Carina, West Capella, and Sonangol Libongos materially increase backlog, push utilization visibility into 2027–2030, and should drive margin expansion as legacy contracts roll to higher dayrates, positioning Seadrill to outperform broader Energy and Fossil Fuels indices through the offshore capex cycle. The amended 13D signals growing strategic interest in the name. I view the shares as a buy with near‑term support at $50 and resistance around $58–$60, targeting a move toward the low‑60s as contracts convert to cash flow.
More Breaking News
Quick Financial Overview
Seadrill Limited (SDRL) has just backed a strong news flow with a sharp move on the tape. Weekly data show the stock grinding from the mid‑$40s to a recent close near $53, with the latest week printing the highest high in the series. Intraday, a 5‑minute candle pushed from around $49.37 to a close near $52.35, signaling aggressive buying into the contract headlines and confirming momentum in the short term.
On the fundamental side, SDRL generated about $1.44B in annual revenue, with revenue growth over 3 and 5 years running hot. Margins are still mixed: EBITDA margin sits near 27.7%, but reported profit margins around breakeven and a very high stated P/E ratio flag that earnings are thin relative to price. Price‑to‑sales around 1.88 and price‑to‑book near 1.01 keep the valuation grounded versus the balance sheet.
The balance sheet looks workable for a cyclical offshore name. Total debt to equity of 0.26, a current ratio near 2.5, and solid liquidity around $339M in cash help SDRL weather downswings. Q4 2025 cash flow from operations was negative and free cash flow was roughly -$63M, reflecting heavy working capital moves and capex. For traders, this mix screams “operational leverage”: when dayrates and utilization are high, earnings can expand fast, but weak periods can burn cash quickly.
Conclusion
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply