ICON plc stocks have been trading up by 11.54 percent amid strong contract wins and robust clinical trial demand.
Key Takeaways Traders Are Watching
- Q3 2026 revenue of $2.02B and adjusted EPS of $2.66 at ICON plc both topped consensus, even as year-on-year revenue and profit slipped.
- Management at ICLR raised 2026 revenue guidance to $8.10–$8.20B and tightened EPS to $10.35–$10.65, signaling confidence in modest outperformance versus Street expectations.
- The company reported very strong bookings, a record backlog, robust free cash flow, and roughly $400M in buybacks, offsetting softer near-term growth guidance.
- RBC maintained an Outperform view on ICLR, pointing to a powerful backlog and industry‑leading book‑to‑bill that support mid‑single‑digit growth in 2027 despite weaker current margins.
- Street views on ICLR are mixed, with Bank of America upgrading to Neutral on improving CRO demand while UBS moved to Neutral, warning client issues may limit bookings and margin upside.
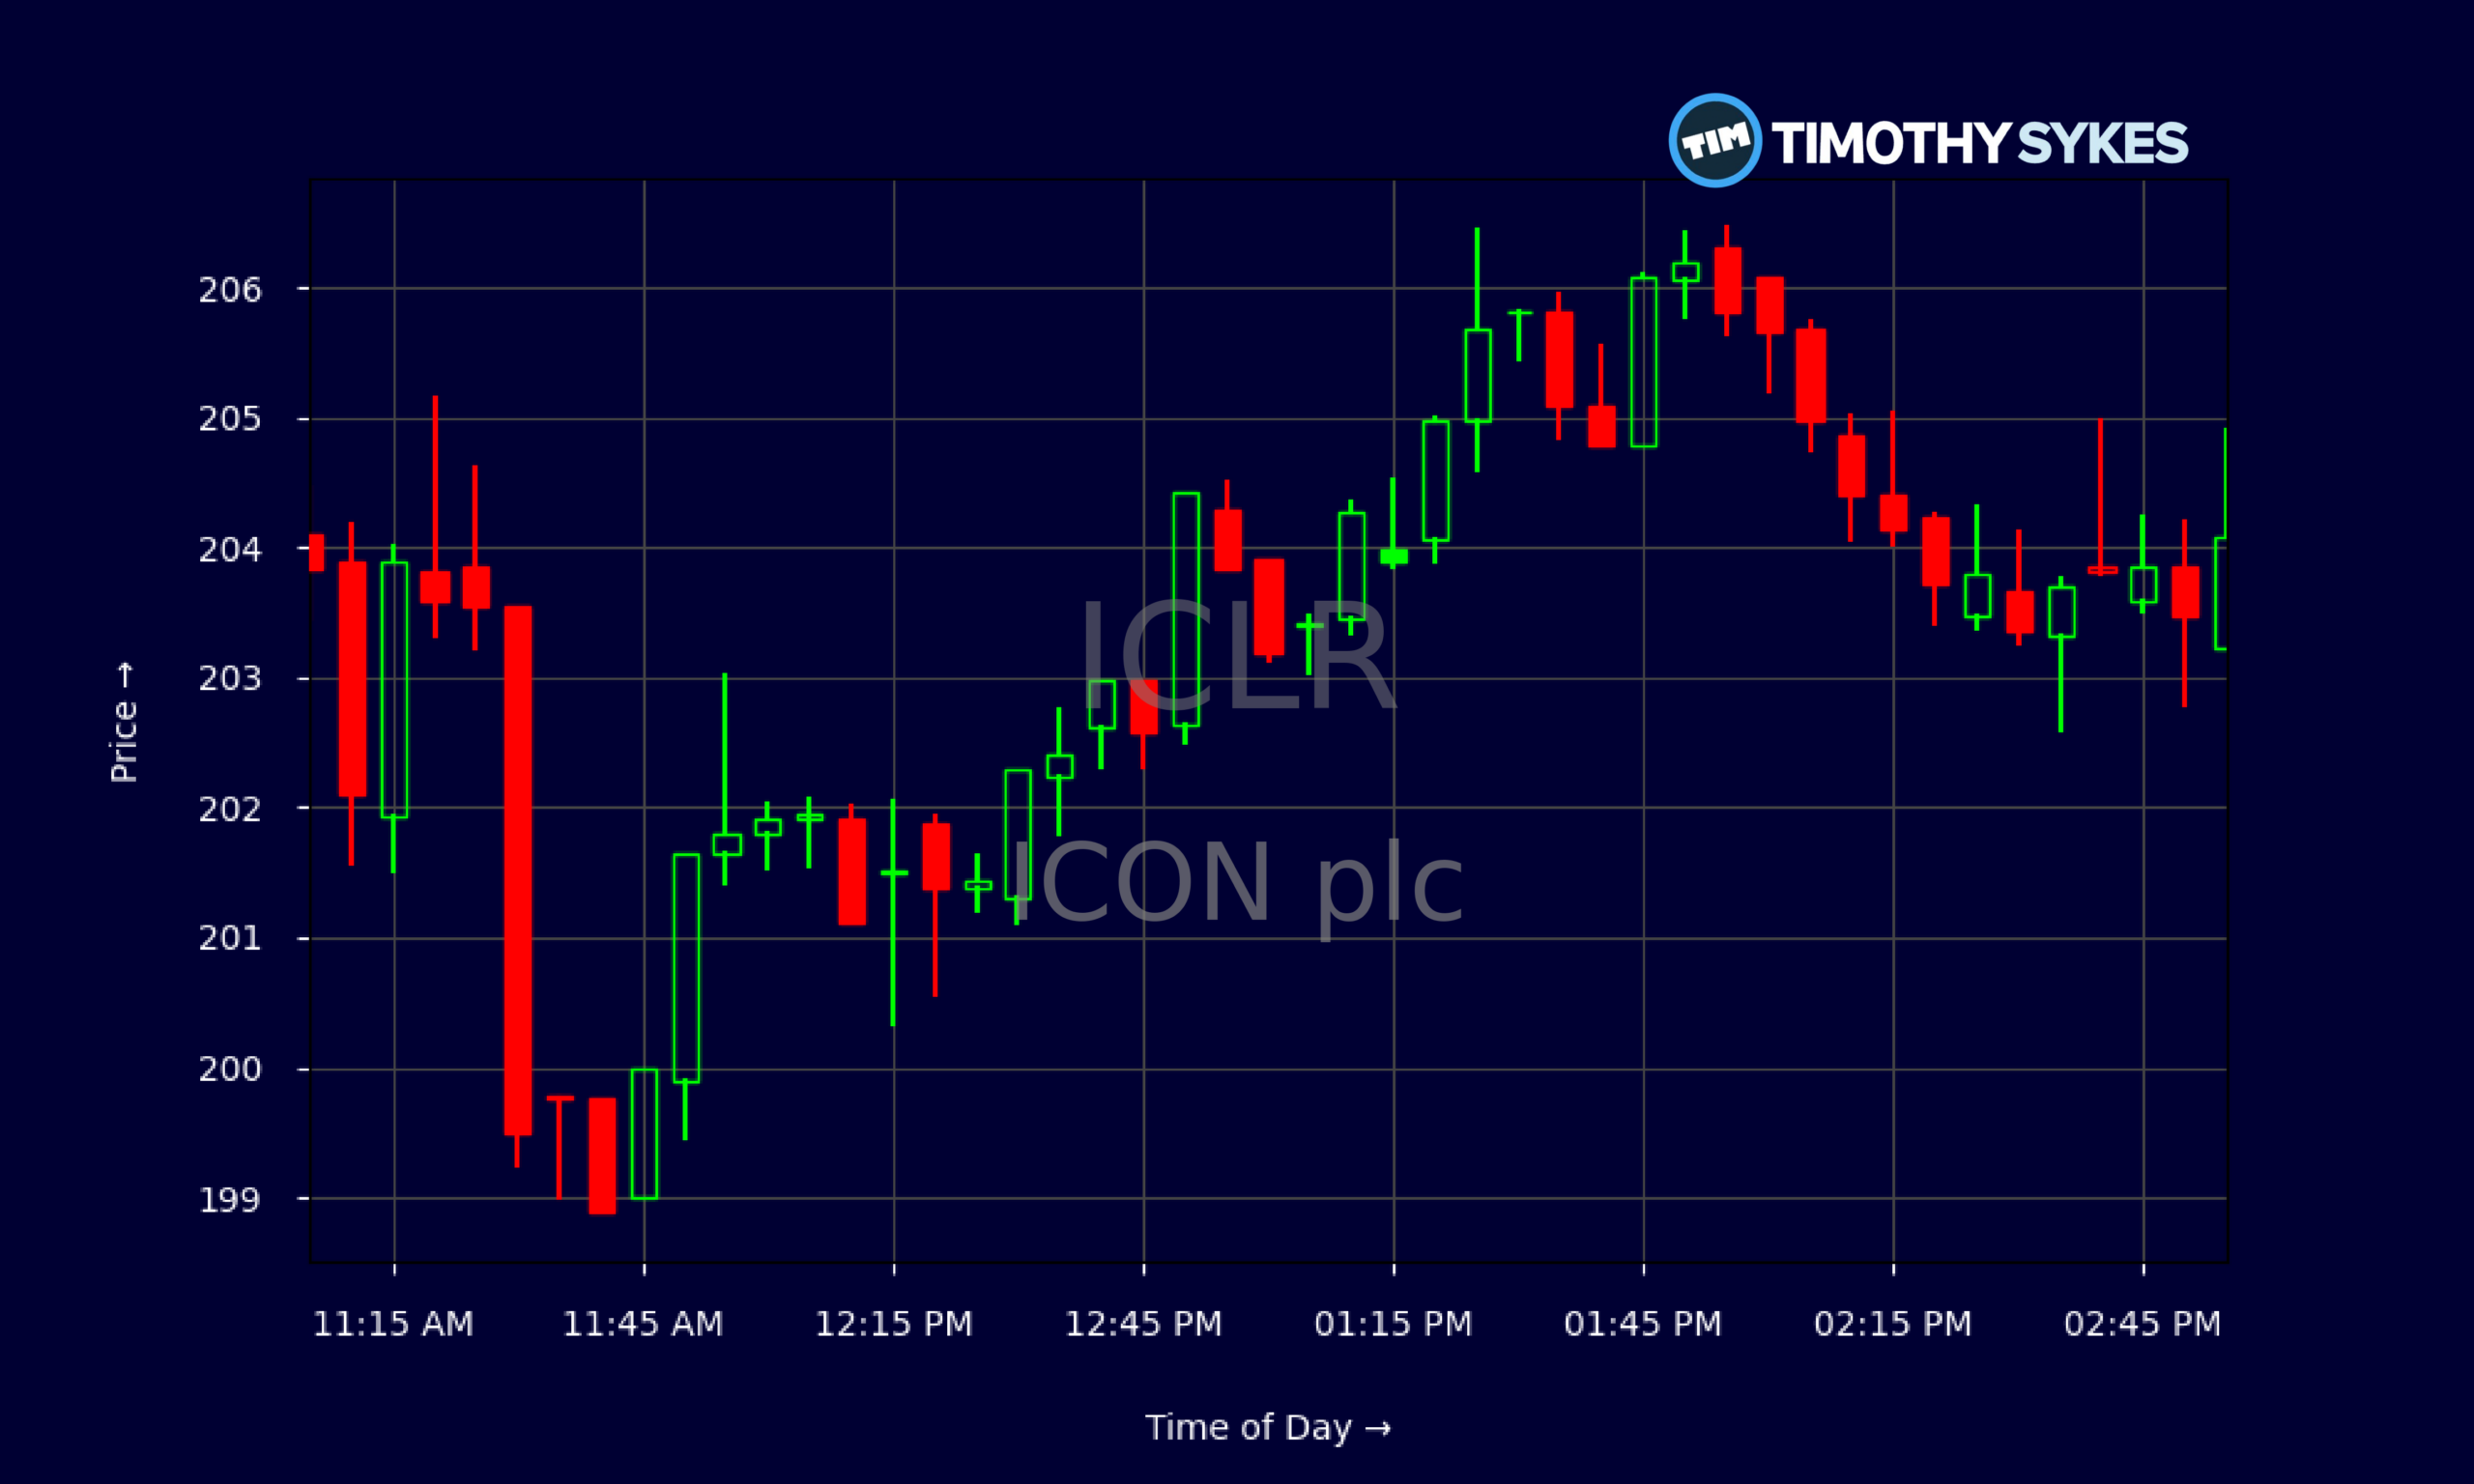
Live Update At 15:02:48 EDT: On Wednesday, October 28, 2026 ICON plc stock [NASDAQ: ICLR] is trending up by 11.54%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
ICLR has quietly turned into a momentum name again. After closing at $182.98 on 2026/10/27, the stock ripped to $204.16 on 2026/10/28, a double‑digit percentage jump in two sessions off the $169‑$171 area from mid‑month. That move came as traders reacted to Q3 numbers that were weak on the surface but better than feared.
ICON plc posted Q3 2026 revenue of $2.02B, just ahead of the $2.01B consensus, with adjusted EPS of $2.66 versus $2.62 expected. Both metrics fell year over year, telling traders that growth has cooled, but the bar was low. The after‑hours pop of about 4.4% shows a lot of that slowdown was already priced into ICLR.
On the daily chart, ICLR has broken above a heavy resistance band in the high $170s to mid‑$180s. The intraday action around $200–$207 shows steady higher lows and tight 5‑minute consolidations, classic signs of controlled accumulation rather than wild speculation.
More Breaking News
Fundamentally, ICLR screens as a premium CRO name. A price‑to‑sales ratio of 1.52 and P/E above 56 tell traders the market is paying up for future earnings, not current margins. Balance‑sheet data show total assets of about $16.27B against equity near $9.19B and a leverage ratio of 1.8, which is manageable for a contract research player with recurring work and a large backlog.
Why Traders Are Zeroing In On ICLR Now
The latest quarter from ICON plc is a classic “expectations game” story. On one side, ICLR reported softer year‑on‑year revenue and profit, confirming that the big pandemic‑era CRO boom has faded. On the other, the company flashed exactly what momentum traders like to see: beats versus consensus, raised guidance, and a strong reaction in the tape.
ICLR modestly beat on both revenue and EPS, then followed that with sequential EBITDA growth and strong demand for its AI‑enabled digital platform. Management did not hide from the slowdown, but they still raised full‑year revenue guidance to $8.10–$8.20B and tightened EPS to $10.35–$10.65. When a management team narrows the range and nudges the top end above the Street, it signals control over the business, not desperation.
The real fuel for the move, though, is forward demand. ICON plc highlighted very strong Q3 bookings, a record backlog, and robust free cash flow. RBC called out that ICLR has an industry‑leading book‑to‑bill and expects at least mid‑single‑digit growth in 2027, even with current organic declines and margins trailing peers. That kind of visibility gives swing traders a narrative to lean on.
At the same time, the analyst tape is not one‑sided. Bank of America upgraded ICLR to Neutral from Underperform and lifted its target to $185, citing healthier CRO demand and solid direct‑fee bookings. UBS, however, moved the stock to Neutral and warned that client‑specific problems could cap bookings and margin expansion. For active traders, that mixed backdrop often creates tradable volatility as each new data point forces the Street to adjust.
Put together, ICLR is trading like a name where bad news on growth was already baked in, and any sign of stabilization or AI‑driven upside becomes a catalyst. The price action from the $160s to above $200 confirms that shift in sentiment.
Conclusion
For traders, ICON plc sits right at the crossroads of slowing reported growth and strengthening forward signals. The Q3 2026 report from ICLR showed year‑on‑year declines in revenue and EPS, yet still edge‑out beats versus consensus, raised 2026 guidance, and a stock that jumped roughly 4.4% after hours and kept running the next day. That tells you the market was positioned for worse.
ICLR now trades at a premium multiple, backed by a record backlog, strong bookings, and about $400M handed back in buybacks. Analyst calls are split between cautious Neutrals and bullish Outperforms, with consensus targets hovering in the high‑$180s to mid‑$190s. That push‑pull keeps ICON plc squarely on the watchlists of momentum and catalyst‑driven traders.
The technical picture backs that focus. ICLR has reclaimed and held the $200 zone after breaking out from a choppy base in the $160s–$180s. As always, traders need to respect both sides of the story: client‑specific risk and weaker margins on one hand, and AI‑enabled platform growth and backlog strength on the other.
In Tim Sykes’ world, discipline around that kind of setup matters more than the story itself: “Cut losses quickly, learn the patterns, and never fall in love with a stock.” As millionaire penny stock trader and teacher Tim Sykes, says, “There is always another play around the corner; don’t chase just because you feel FOMO.”. ICLR gives traders a live case study of that mindset in action, strictly for educational and research purposes, not as any kind of investment advice.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply