Norwegian Cruise Line Holdings Ltd. stocks have been trading up by 3.54 percent amid strong post-pandemic travel demand optimism.
Key Takeaways For NCLH Traders
- Cruise names are riding Carnival’s strong Q3 report, with NCLH benefiting from a sector rerating on multi‑year demand and pricing strength.
- A $750M senior-notes deal due 2031 to refinance nearer-term debt briefly lifted NCLH about 2.7% in premarket trading as traders welcomed reduced refinancing risk.
- Major Wall Street firms cut NCLH price targets into the high‑teens but still rate the stock overweight, with a mean target around $18–$19 versus a mid‑teens share price.
- Citi flags higher fuel and interest costs as the main earnings headwinds for NCLH, while stressing that Q4 demand and bookings remain solid.
- New bookings opened for Norwegian Bella, a large-capacity ship launching European routes in 2028, added to NCLH’s growth story and coincided with a roughly 3% share price pop.
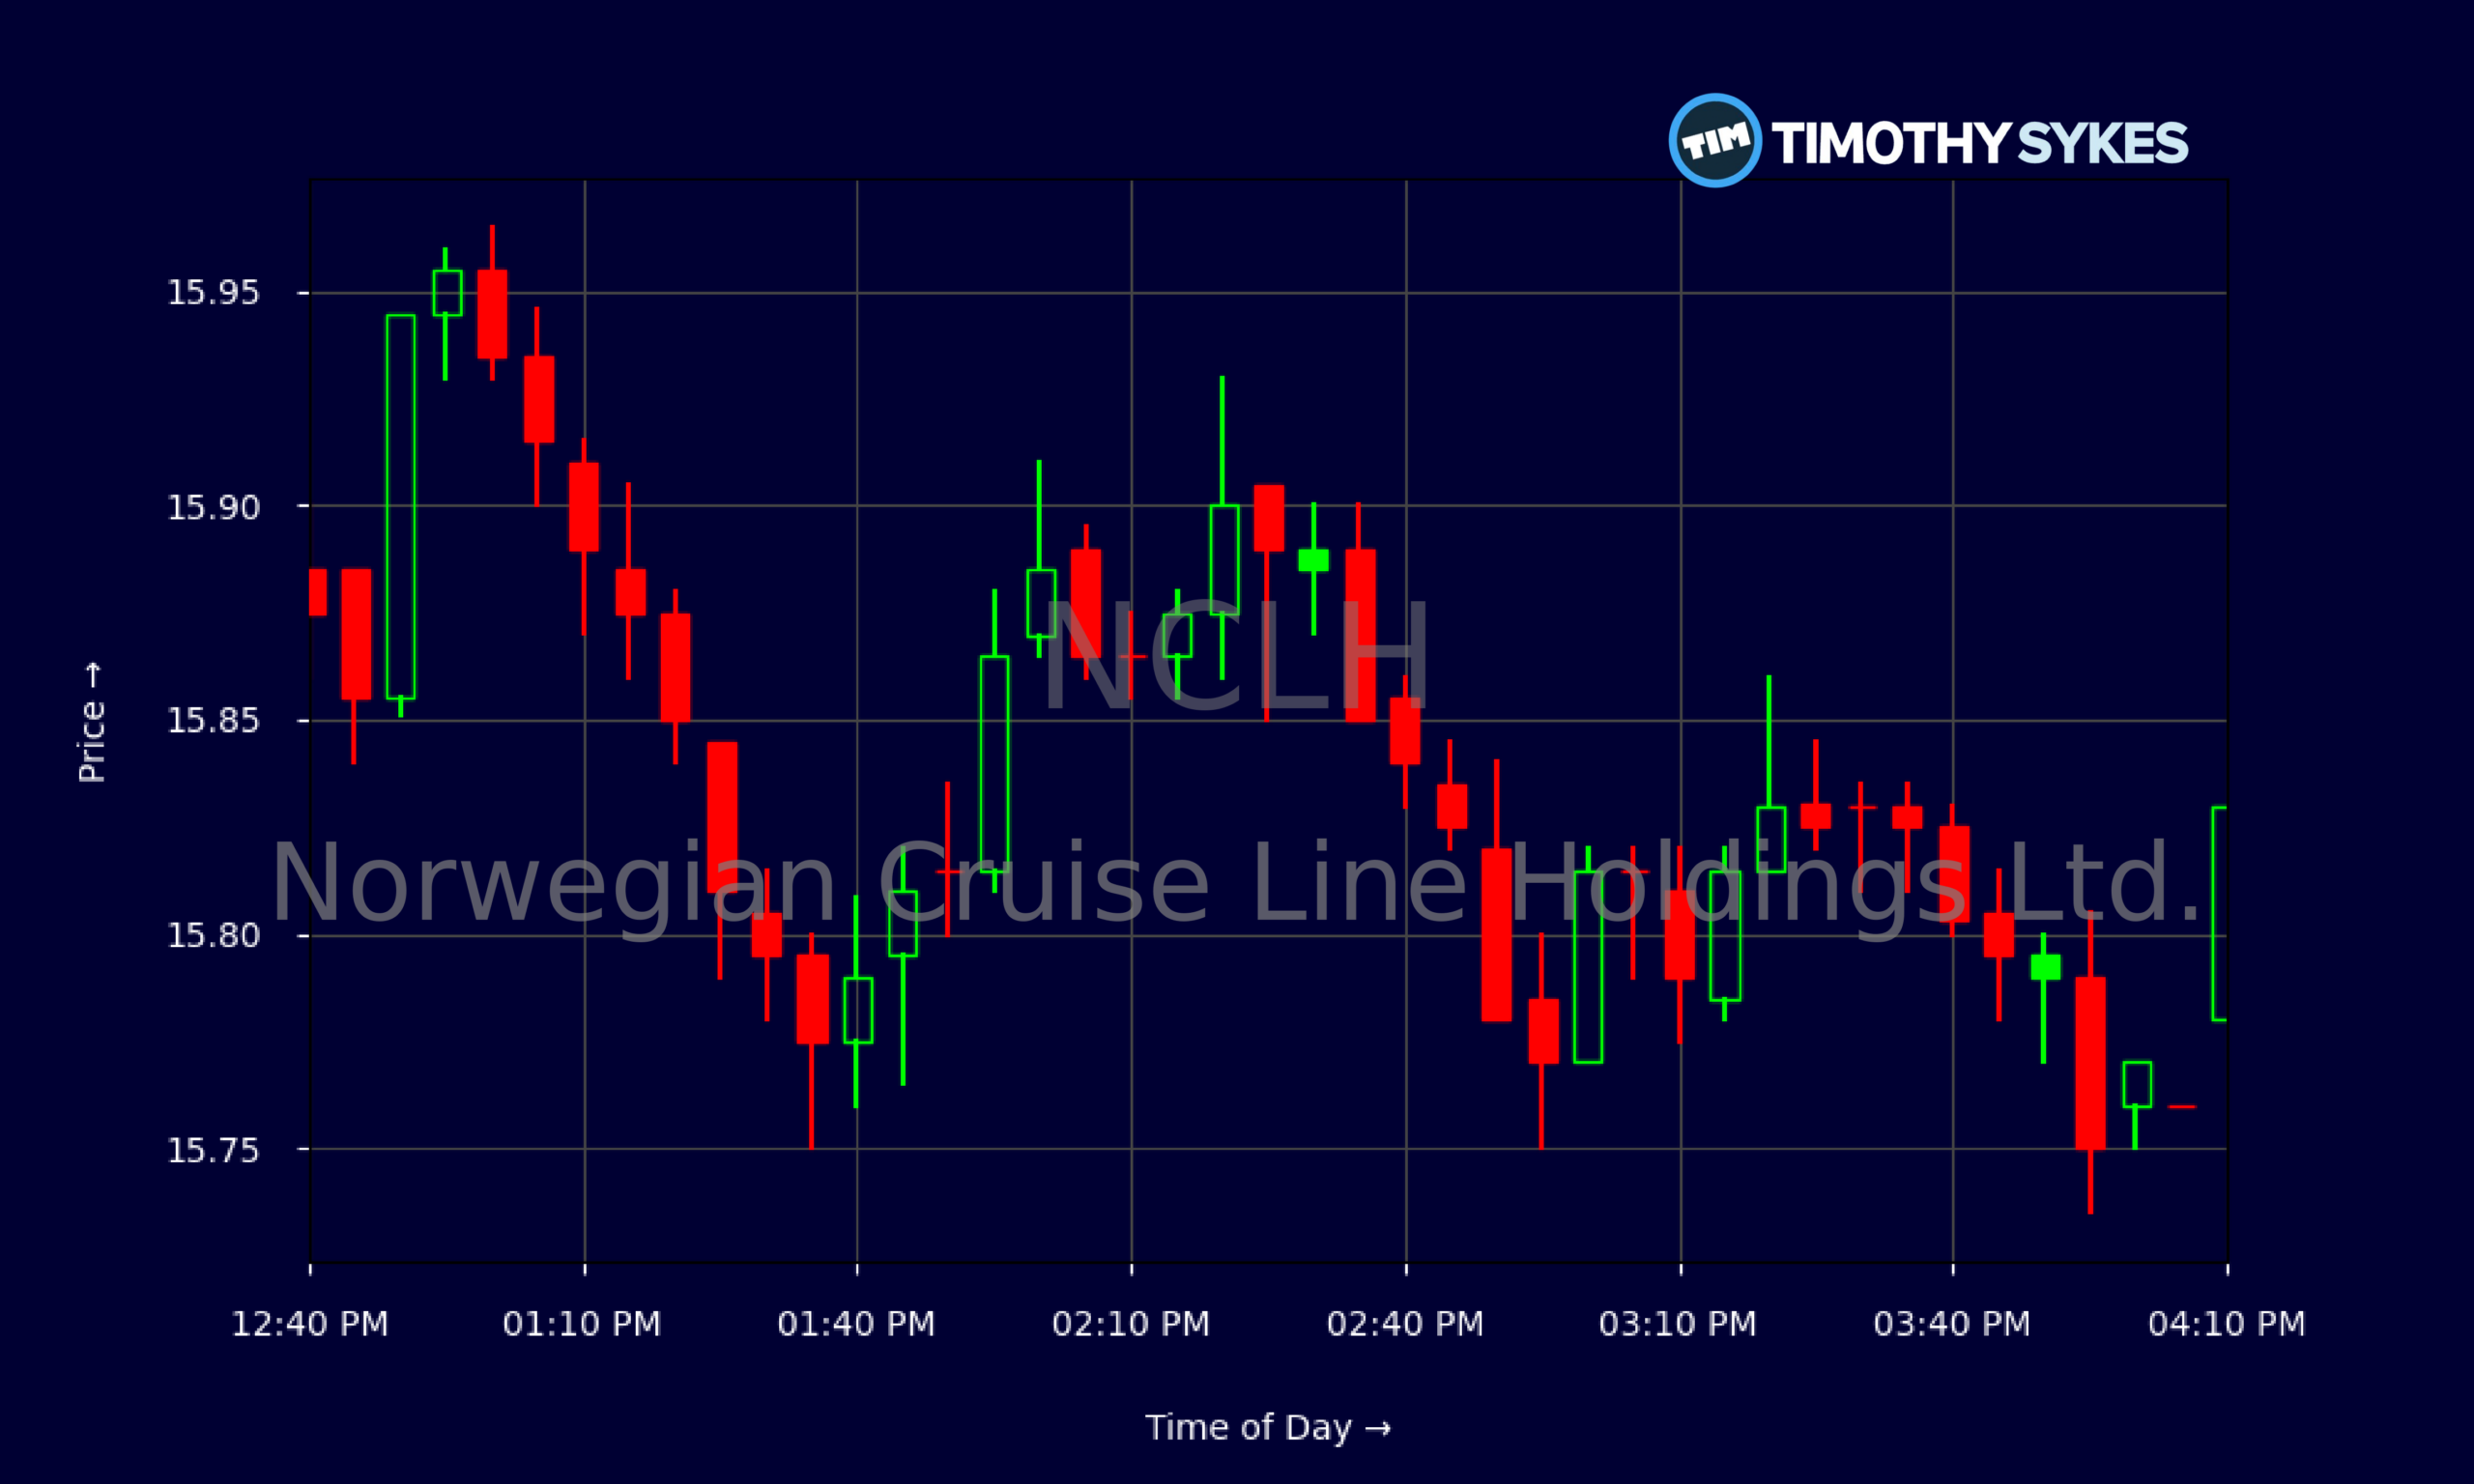
Live Update At 16:47:00 EDT: On Tuesday, October 27, 2026 Norwegian Cruise Line Holdings Ltd. stock [NYSE: NCLH] is trending up by 3.54%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
Norwegian Cruise Line Holdings Ltd. is acting like a classic reopening and deleveraging trade. The stock has chopped around the mid‑teens lately, closing near $15.75 after several sessions holding the $15–$16 zone. That tells traders NCLH has a base, but not yet a breakout.
On the daily chart, NCLH keeps bouncing off the low‑$15s and failing near $16.14. That’s your immediate trading range. Intraday, the 5‑minute tape shows tight action around $15.75–$15.90 for most of the afternoon, signaling balanced buyers and sellers rather than panic.
Fundamentally, recent quarterly revenue is about $2.64B, with gross margin near 73.7%. EBITDA of roughly $691M and EBIT margin near 15.8% show the core cruise operations are profitable again. Net income around $223M translates to diluted EPS of $0.48, putting NCLH near a single‑digit P/E of about 9–10 times.
More Breaking News
But leverage is the shadow over this name. Total debt is heavy, with debt-to-equity above 5.8 and a current ratio of only 0.2. NCLH throws off solid operating cash flow — about $603M in the last reported quarter and $145M in free cash flow — yet the balance sheet still dominates the trading thesis.
Why Traders Are Watching NCLH Right Now
NCLH is sitting at the crossroads of three big themes: a cruise-demand upcycle, aggressive debt management, and a cautious but still bullish Wall Street.
First, demand. Norwegian Cruise Line has been pulled higher alongside Royal Caribbean and Viking after Carnival delivered a strong Q3 and talked up bullish multi‑year demand. That external proof of pricing power and occupancy matters. It signals the whole cruise group, including NCLH, is in a rerating phase where traders are willing to pay more for the same earnings if the growth runway looks real.
Second, the balance sheet story. NCLH’s subsidiary is issuing $750M of new senior notes due 2031. The cash is earmarked to refinance 6.125% notes due 2028, repay about $176.3M on the revolver, and prepay $42.2M of export‑credit backed debt. There’s no new growth cash here, just liability management. But the market liked it at first — shares jumped roughly 2.7% premarket on the news — because pushing maturities out to 2031 lowers near-term refinancing risk.
Third, the Street’s stance. Citi, BofA Securities, Deutsche Bank, Stifel, Wells Fargo, TD Cowen, and others have all trimmed their NCLH price targets into the high‑teens to around $18–$19 on average. They point to higher fuel and interest costs and lingering macro worries. Yet most still rate Norwegian Cruise Line overweight or Buy. Citi kept a Buy at $19, highlighting that Q4 demand is solid and that management didn’t hike full‑year guidance mainly because of fuel volatility, not weak bookings.
On top of that, Norwegian Cruise Line opened bookings for Norwegian Bella, a new large‑capacity ship sailing seven‑day European voyages from 2028 alongside Norwegian Aura. Traders rewarded that with about a 3% share price rise, reading it as confirmation that NCLH can still grow yields and sell future inventory years in advance.
Conclusion
For active traders, NCLH is a tug‑of‑war between strong demand and heavy debt. The tape shows a stock consolidating in the mid‑teens while the Street’s average target sits several dollars higher, around $18–$19. That spread reflects the risk-reward: plenty of upside if the cruise upcycle and cost controls hold, but leverage and consumer health worries limit how aggressive traders want to get.
Norwegian Cruise Line’s refinancing of $750M in notes out to 2031 shows management is fully focused on survival and stability. It modestly improves the debt profile but doesn’t erase the leverage overhang. At the same time, positive signals like Norwegian Bella bookings and sector-wide strength off Carnival’s Q3 commentary show that NCLH is not fighting demand; it is fighting its own capital structure.
A key near-term catalyst now is NCLH’s Q3 2026 report, slated for 2026/10/29. Traders will be laser‑focused on booking trends, cost commentary, and any update on further debt moves. As Tim Sykes likes to remind his community, “Patterns repeat, but only for traders who study them and cut losses fast.” As millionaire penny stock trader and teacher Tim Sykes, says, “The goal is not to win every trade but to protect your capital and keep moving forward.”. For NCLH, the pattern is clear: strong charts when demand headlines dominate, sharp pullbacks when debt and macro fears return — and that’s where disciplined trading plans matter most.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply