
Diamondback Energy Inc. stocks have been trading up by 4.39 percent after bullish coverage highlighted strengthening oil price tailwinds.
What Traders Need To Know
- Scotiabank initiated coverage on Diamondback Energy with an Outperform rating and a $250 target, citing strong free cash flow yields, appealing valuation, and efficient capital use despite macro headwinds.
- Recent Q3 results showed strong realized commodity prices for Diamondback Energy but also sizable cash and non-cash hedging losses, while the share count stayed relatively stable.
- BMO Capital raised its price target on Diamondback Energy to $224 from $215 and kept an Outperform rating, fitting into an overweight Street view with mean targets around the mid-$230s.
- Morgan Stanley, Jefferies, Roth Capital, and JPMorgan all raised targets on Diamondback Energy, with JPMorgan now at $253 as the stock continues to carry an average overweight rating.
- Insider Charles Alvin Meloy sold 33,333 shares for about $6.1M but still controls roughly 788,000 shares, leaving him heavily exposed to Diamondback Energy’s future performance.
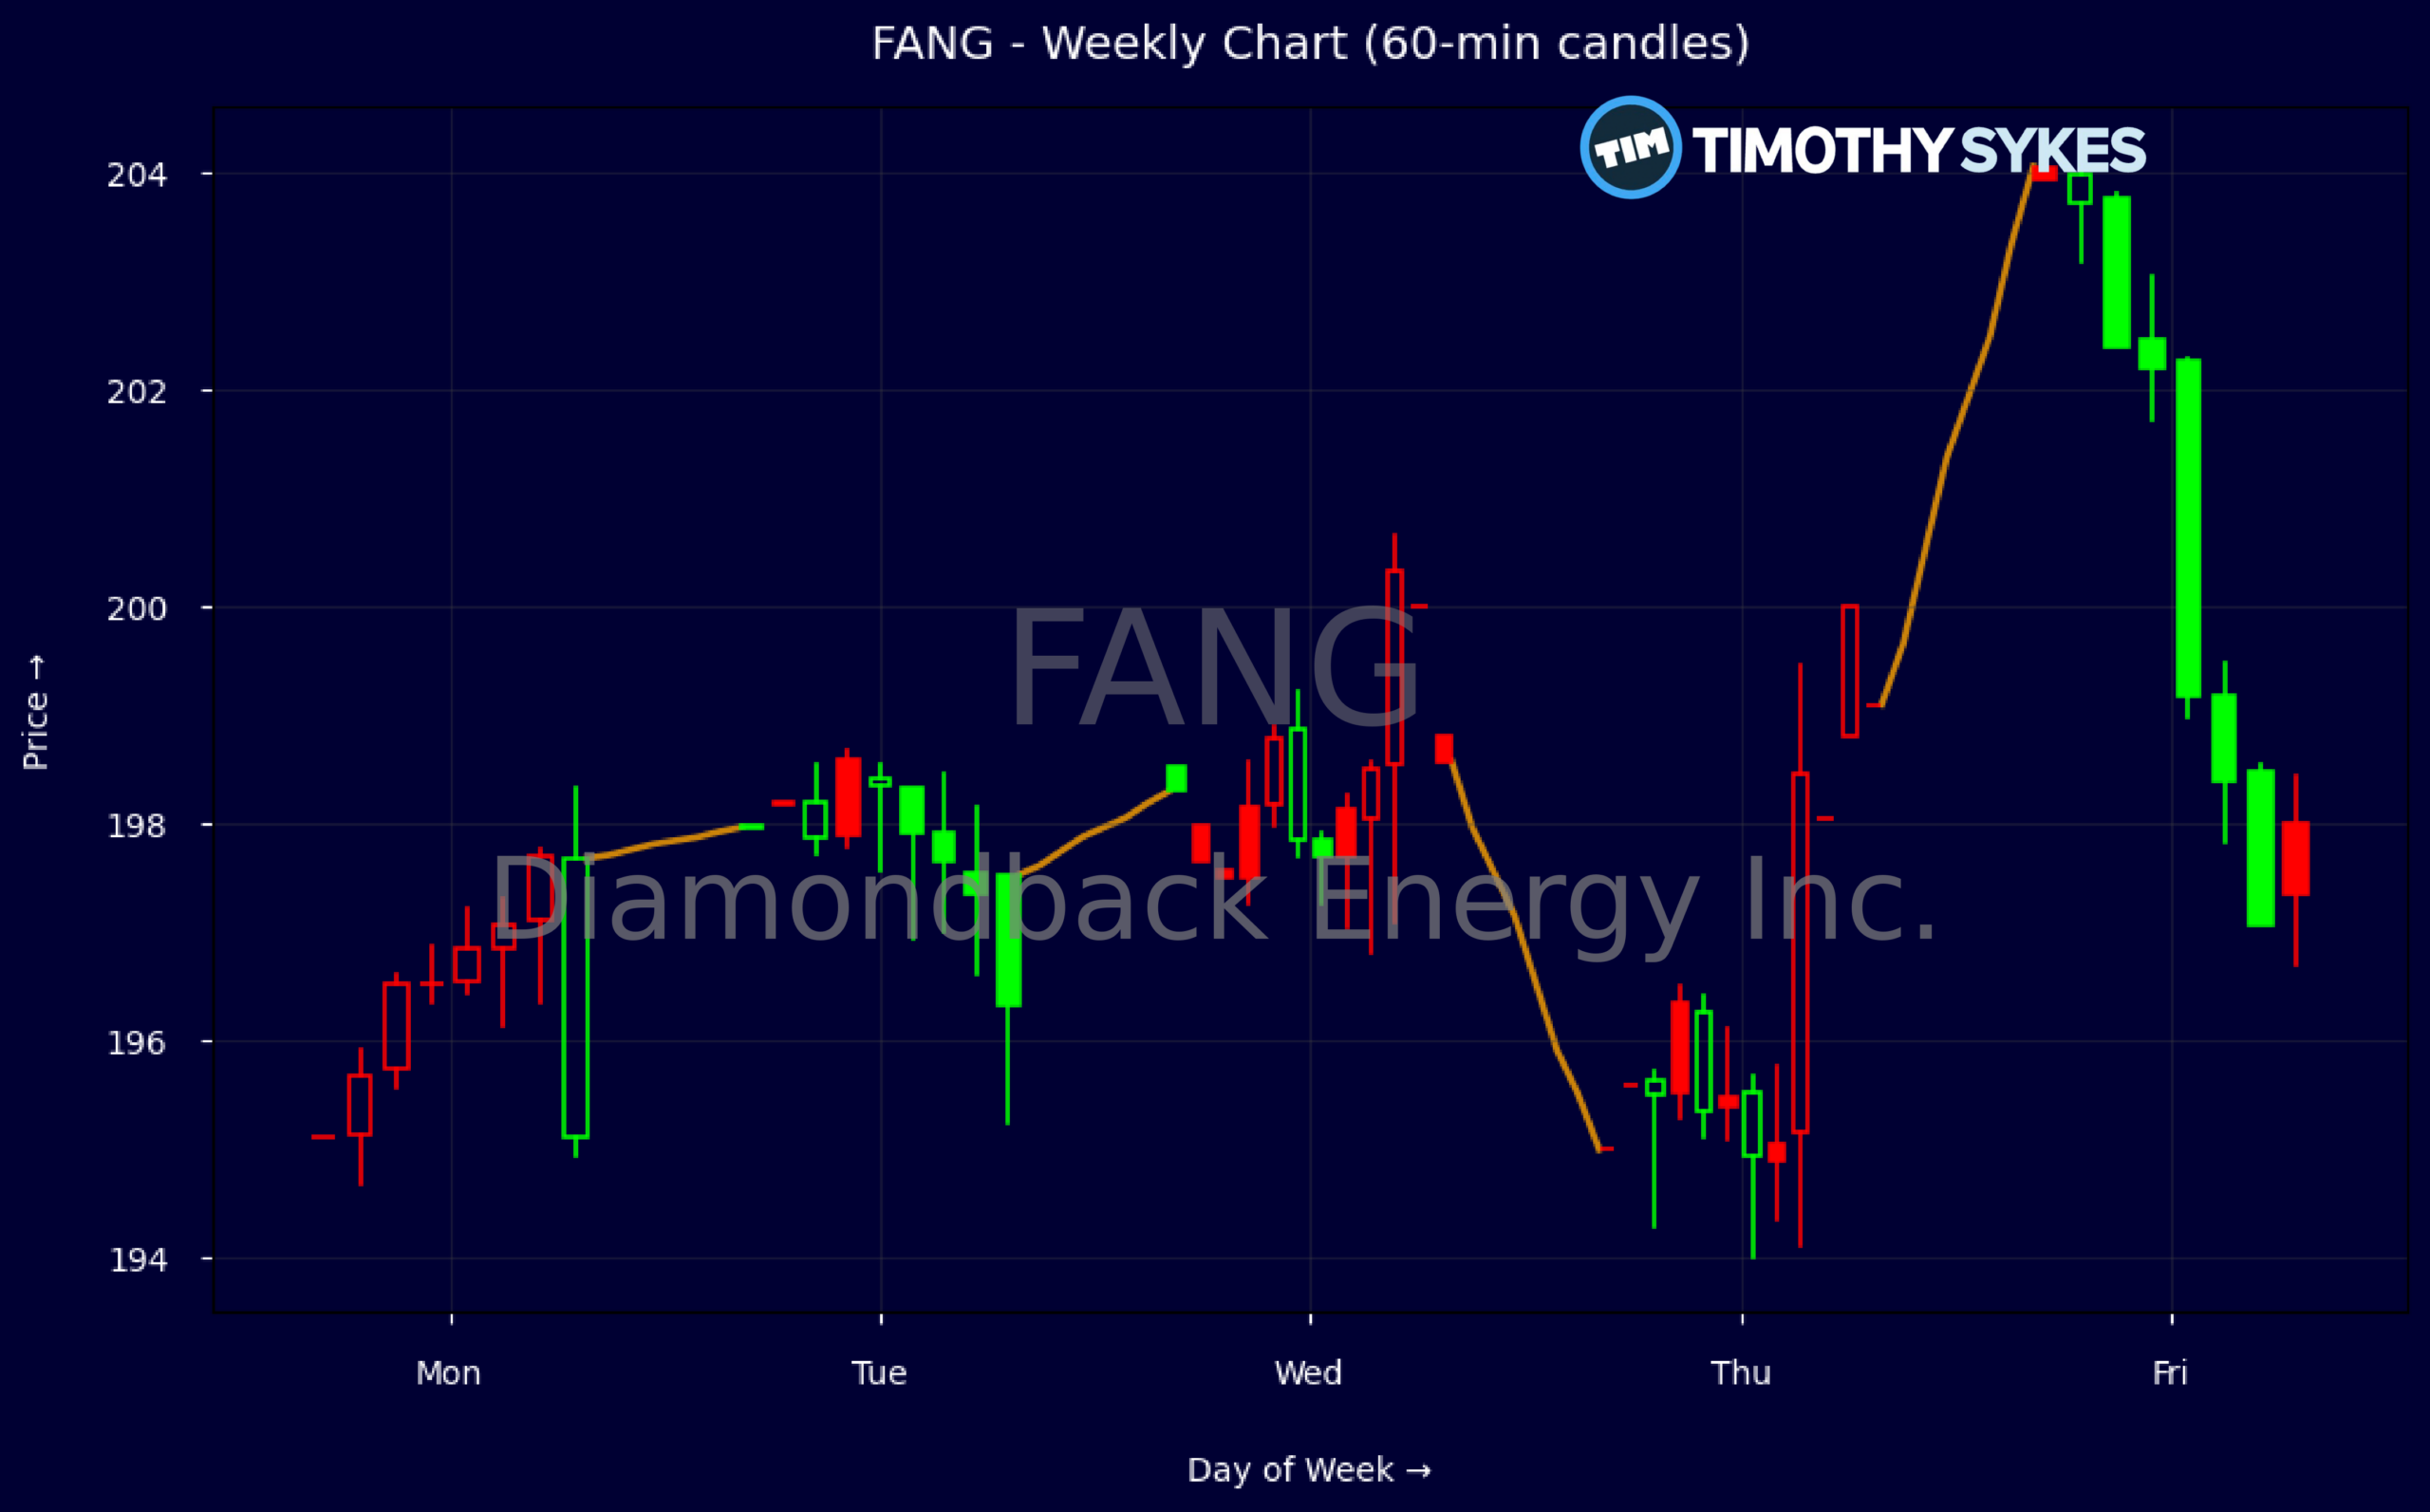
Weekly Update Oct 12 – Oct 16, 2026: On Friday, October 16, 2026 Diamondback Energy Inc. stock [NASDAQ: FANG] is trending up by 4.39%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Energy industry expert:
Analyst sentiment – positive
Diamondback Energy sits in the top tier of Permian E&Ps, with scale-driven cost advantages and strong cash generation. EBIT margin of 12.6% and EBITDA margin of 43.5% on $14.9B revenue underscore robust upstream economics, while revenue growth of 26.9%/31.3% over three and five years outpaces most large-cap peers. Balance sheet strength is clear: debt-to-equity of 0.33, interest coverage 25.6x, and EV/FCF near 6x support sustained shareholder returns and selective M&A.
Technically, FANG remains in a firm intermediate uptrend, with the weekly tape stair-stepping from $195 to $204 and consistent higher closes, confirming institutional accumulation around $195 support. Five-minute candles show responsive buying on dips sub-$200, with volume spikes confirming demand into strength. Dominant trend is bullish; pullbacks into the $197–$199 zone offer high-probability entries with a tight trading stop below $195 and upside potential to retest and break above $205 near term.
Near-term catalysts are constructive: multiple brokers (Scotiabank, BMO, JPMorgan, Morgan Stanley, Jefferies) have raised targets into the $215–$253 range, with a consensus around $235–$240, reflecting confidence in free cash flow durability despite hedge losses. Relative to Energy and Fossil Fuels benchmarks, FANG offers superior FCF yield and capital efficiency at only a modest premium P/E. I see fair value at $235 over 6–12 months, with strong support at $195 and resistance at $210 then $225.
More Breaking News
Quick Financial Overview
Diamondback Energy Inc. (FANG) is trading just above $200, with recent weekly closes moving from about $195 to roughly $204, showing a steady grind higher rather than a parabolic spike. The five-minute chart backs that up: intraday trade around $200–$204 stayed tight, with shallow pullbacks being bought and closes near session highs. For short-term traders, that kind of controlled trend often signals orderly accumulation rather than speculative blow-off.
On the Street side, Scotiabank’s new Outperform rating with a $250 target, along with BMO, JPMorgan, and others clustering in the low-to-mid $200s, puts consensus targets well above the current price zone. That sets up a clear “valuation gap” narrative, but traders need to remember it is just potential, not a guarantee of further upside. The recent deal selling mineral and royalty interests to Viper Energy also hints at continued portfolio optimization rather than growth at any cost.
Fundamentally, Diamondback Energy is throwing off serious cash. Trailing revenue is about $14.9B, with EBITDA margin near 43.5% and pretax margin around 37%, supporting robust operating cash flow of roughly $3.6B and free cash flow of about $2.2B last quarter. Leverage looks manageable with total debt-to-equity around 0.33 and interest coverage above 25x, while a dividend yield near 2.25% plus a price-to-free-cash-flow near 6.1 suggest the market is not overpaying for that cash. The main watch item on the financial side is a relatively low current ratio near 0.5 and hedging losses that can distort quarterly optics even when the core business performs well.
Conclusion
Diamondback Energy Inc. is sitting in a sweet spot where firm operational delivery, bullish analyst coverage, and steady price action are lining up. The stock has stair-stepped from the mid-$190s into the low $200s while the Street talks targets from about $215 up to $253, with an average still well above spot. For traders, that gap between price and targets acts like an overhang of potential energy, but it only matters if future quarters confirm the current story.
The latest Q3 read shows exactly what short-term traders must track: strong commodity realization on one side, sizable hedge losses on the other. Price will respond to how the market weighs those pieces. News around Viper Energy drop-downs, longer-dated 2027 plans, and clarity on assets like Barnett can all become catalysts that either extend this trend or break it. Risk sits mainly in macro oil swings, hedge impacts, and the balance sheet’s tight working capital.
For now, FANG trades like a liquid, institutionally supported name with defined levels: support forming near $195 and momentum pressing toward recent $204 highs. As I tell my students, “Your job isn’t to predict the future, it’s to read the tape, respect your levels, and let the market prove you right before you size up.” That mindset lines up with the broader trading principle that you let the price action lead and adjust accordingly—As millionaire penny stock trader and teacher Tim Sykes, says, “You must adapt to the market; the market will not adapt to you.”. This stock fits that playbook for disciplined, research-driven traders.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply