
Applovin Corporation stocks have been trading up by 28.61 percent following strong growth projections and upbeat investor sentiment.
Key Takeaways For APP Traders
- Q3 saw EPS of $4.30 vs. $4.03 consensus and revenue of $2.18B vs. $2.07B, showing APP’s profitability and growth outpaced Wall Street expectations.
- Year over year, Q3 EPS jumped from $2.45 to $4.30 and revenue from $1.41B to $2.18B, with Q4 revenue guided to $2.37B–$2.40B ahead of the $2.25B Street estimate.
- Management issued Q4 guidance of $2.365B–$2.395B in revenue and $1.995B–$2.025B in adjusted EBITDA, pointing to very strong expected profitability for APP.
- The board approved a $3.2B boost to APP’s repurchase plan, taking total buyback authorization to $3.6B and signaling strong confidence in the company’s future.
- A securities class action now alleges APP misled markets on AI model improvements and ad product ramp, following softer e‑commerce ad data, a Q2 revenue miss, and a ~34% cumulative share slide.
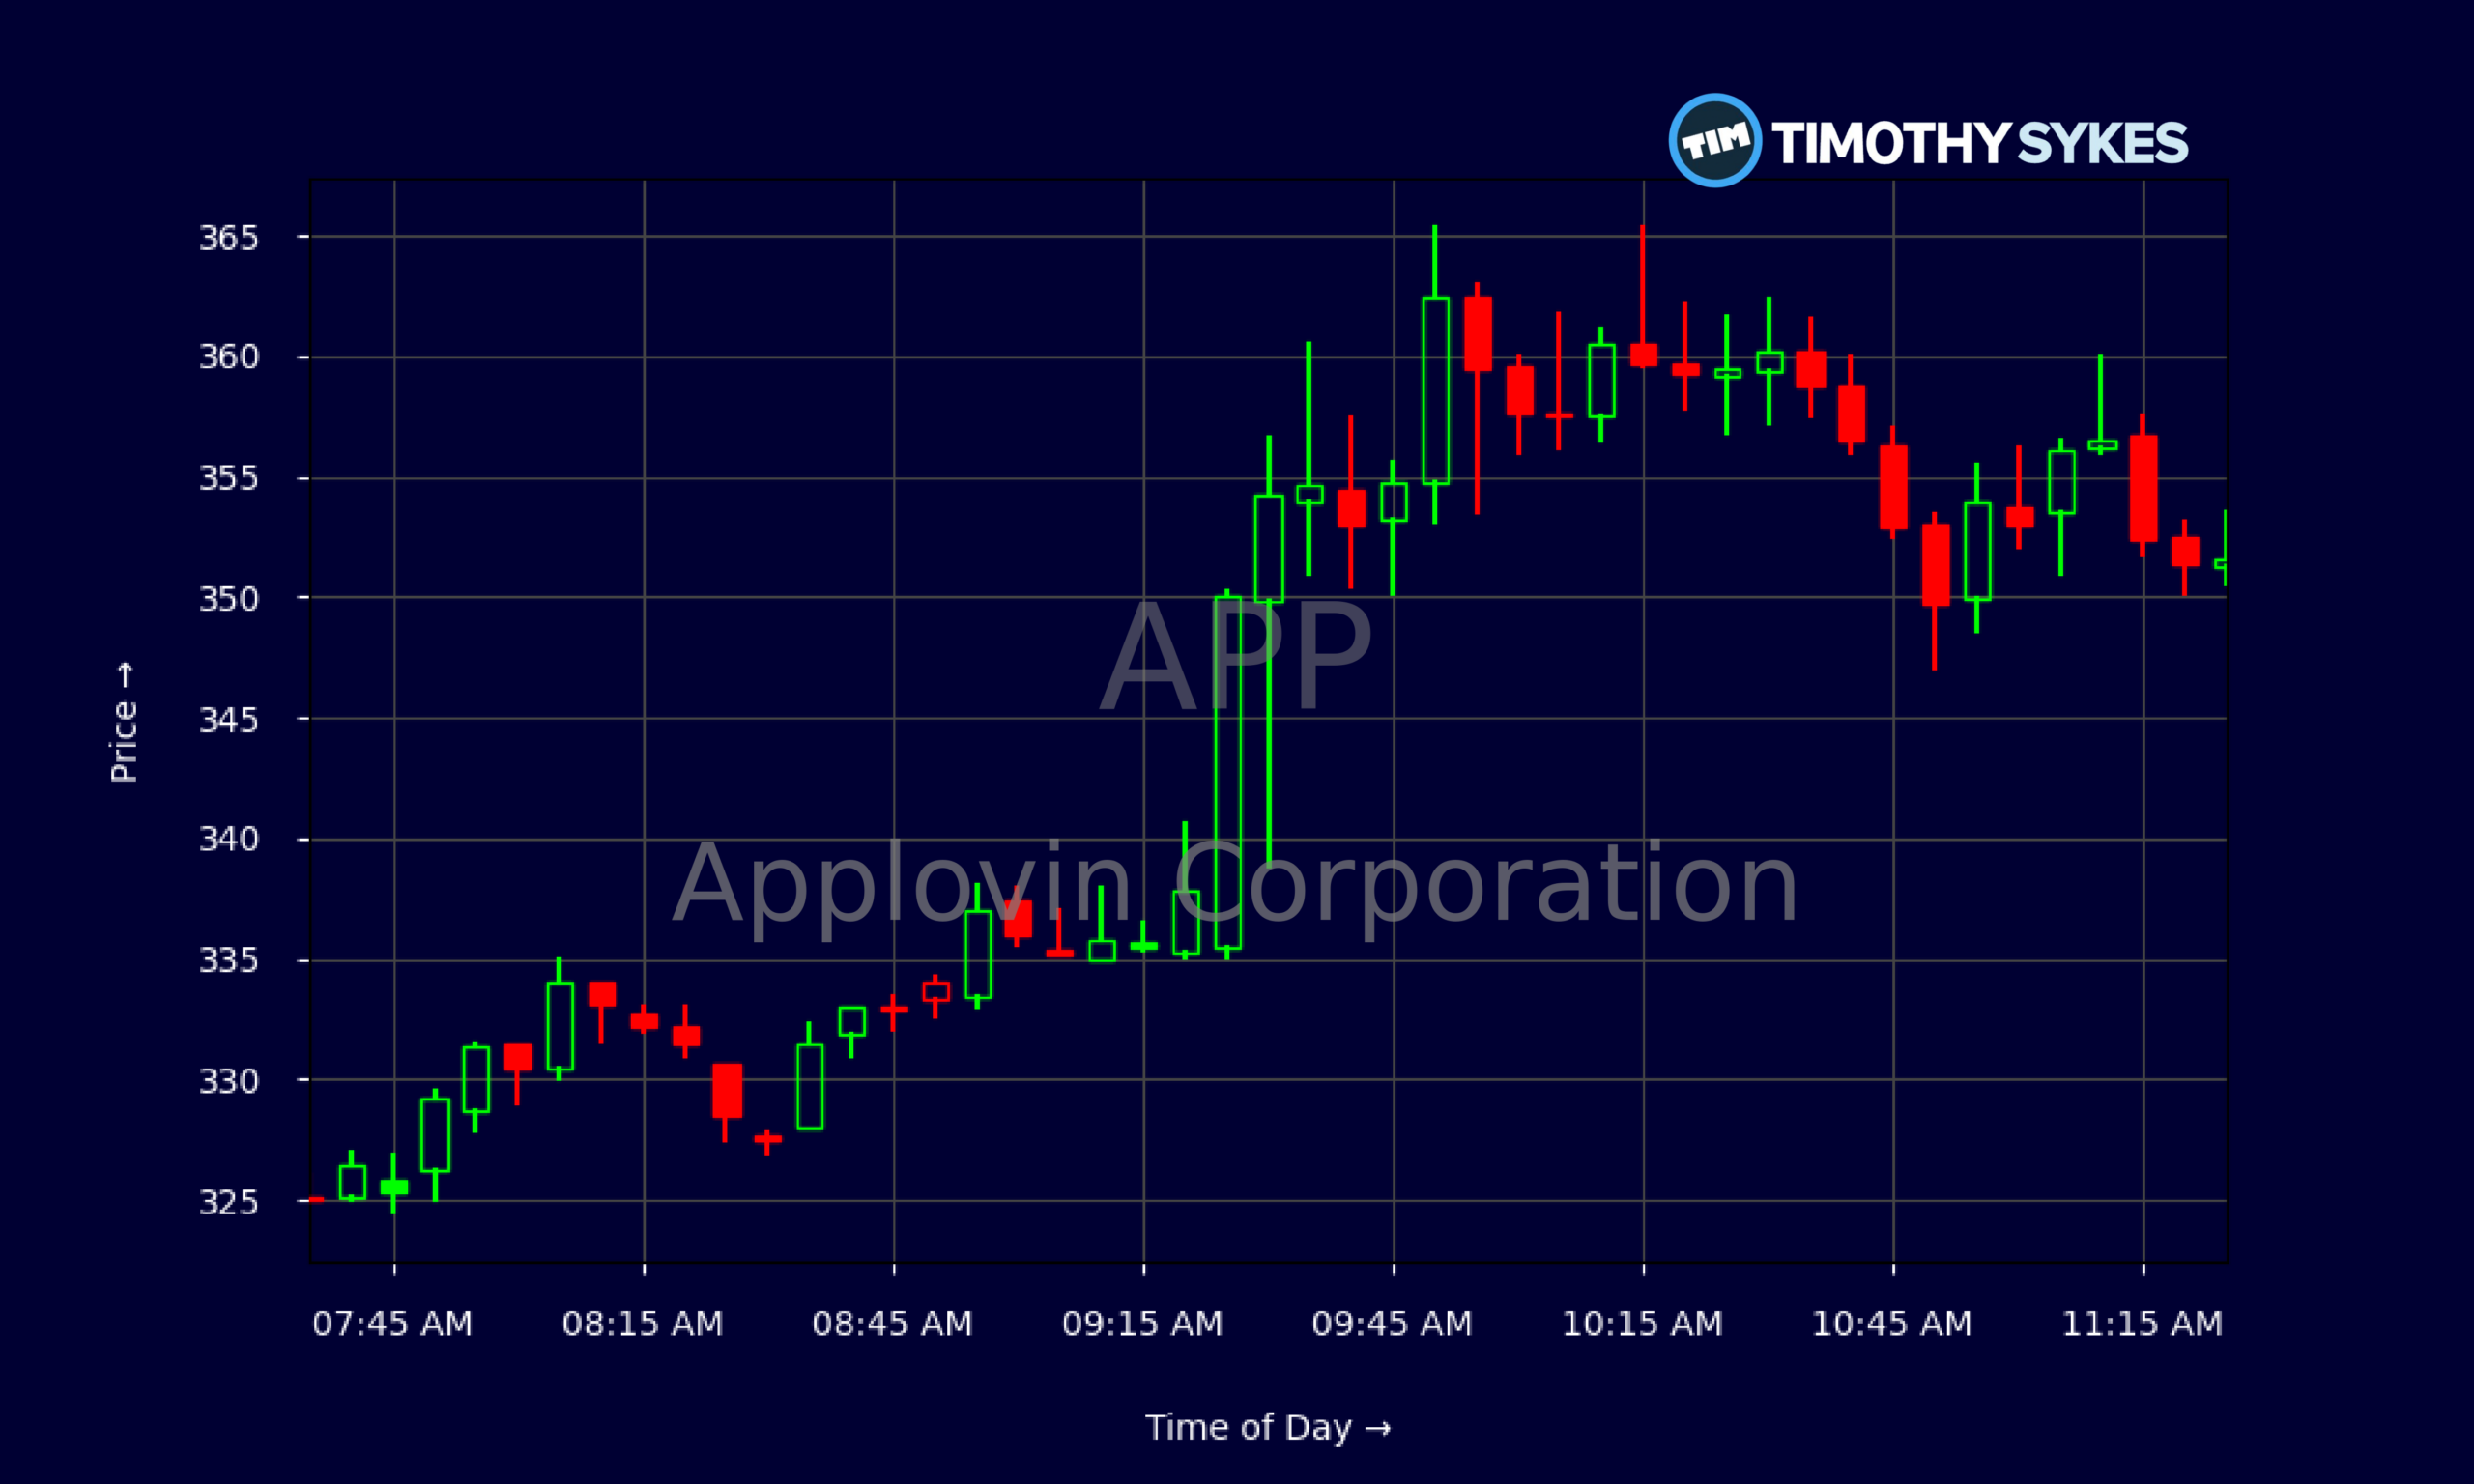
Live Update At 11:34:21 EST: On Thursday, November 05, 2026 Applovin Corporation stock [NASDAQ: APP] is trending up by 28.61%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
APP is trading like a momentum monster after its latest numbers. The daily chart shows the stock ripping from a prior close of $271.75 on 2026/11/04 to $348.31 on 2026/11/05, a gain of roughly 28%. That kind of single‑day move tells traders there was serious surprise baked into the quarterly update.
Intraday, APP spiked to an early high around $365, then faded into the high $340s. That push-and-pull is classic post‑earnings action: shorts scrambling early, then profit‑taking from fast money. For day traders, the 5‑minute candles show a wide, liquid range between roughly $339 and $365 — plenty of room for both breakout and fade setups.
More Breaking News
Under the hood, APP’s income statement for the recent period lists revenue of about $2.18B and net income of roughly $1.44B, with diluted EPS around $4.30. That’s a big jump from the prior year’s $2.45 EPS and $1.41B revenue. For short‑term trading, that acceleration, plus APP’s strong cash generation and share count north of 330M diluted, paints the picture of a large‑cap name acting like a smaller, high‑beta growth stock.
Why Traders Are Watching APP Right Now
APP is sitting at the center of several powerful storylines, and traders are reacting to all of them at once. First, the company delivered Q3 revenue of $2.18B versus a $2.07B consensus, while EPS hit $4.30 against expectations of $4.03. That is a clean beat on both the top and bottom line, backed by year‑over‑year growth from $1.41B revenue and $2.45 EPS. When a name puts up that kind of acceleration, it immediately hits the momentum screens.
Guidance turned the beat into a “beat‑and‑raise.” APP told the Street to expect Q4 revenue between $2.37B and $2.40B, better than the roughly $2.25B analysts were modeling. Another update framed Q4 revenue guidance in a very similar $2.365B–$2.395B band and paired it with adjusted EBITDA of $1.995B–$2.025B. For traders, that combination says one thing: APP expects strong growth and fat margins to continue.
The capital‑return story adds more fuel. APP’s board approved a $3.2B increase to its share repurchase plan, taking total buyback authorization to $3.6B as of the end of October. Buybacks at that scale can be a real tailwind on dips, especially for swing traders looking for support levels.
The Street is adjusting, not abandoning, the story. RBC trimmed its APP price target to $500 from $575 but kept an Outperform rating, citing solid guidance and strong daily average revenue growth. UBS cut its target to $414 from $790, still with a Buy stance, pointing to slower consumer trends and tougher gaming competition but expecting better non‑gaming performance. Macquarie also lowered its target to $460. The common thread: targets down, but ratings broadly positive and average targets still well above where APP is trading, which keeps the ticker firmly on watchlists.
On top of that, APP’s Wurl unit released a CTV Trends Report and rolled out a Content Intelligence Platform aimed at fixing data and transparency gaps across more than 140B monthly CTV ad impressions. That gives traders a longer‑term angle: APP pushing beyond core app ads into connected TV, where signal quality is a big problem and a big opportunity.
Balancing the bull case, there is a securities class action claiming APP misled the market about how fast its AI models were improving and how quickly its ad/AI tools would ramp. The complaint follows softer e‑commerce ad data, a slight Q2 revenue miss, a roughly 34% cumulative drawdown, and multiple analyst target cuts. For traders, that legal overhang is real headline risk, especially if any new disclosures change how the market views APP’s AI narrative.
Conclusion
Right now, APP is a textbook momentum name driven by hard numbers, not just hype. The company just printed Q3 revenue of $2.18B and EPS of $4.30, well ahead of consensus and sharply above last year’s $1.41B and $2.45. Q4 guidance in the $2.37B–$2.40B revenue range, and adjusted EBITDA around the $2.0B mark, tells traders that APP expects the good times to continue. Add a $3.6B total buyback authorization and APP starts to look like one of those names where strong fundamentals meet aggressive capital returns.
At the same time, APP’s story is not risk‑free. Target cuts from RBC, UBS, and Macquarie show that, even with an overall Buy‑leaning stance and average price targets still above the current quote, the Street is recalibrating expectations. The pending AI‑focused securities class action also hangs over the stock and can inject volatility into any extended run.
For active traders, that mix of explosive earnings momentum, heavy volume breakouts, and real headline risk is exactly where opportunity lives. As Tim Sykes likes to remind his students, “The market rewards preparation, not hope — study the catalysts, plan the trade, and always be ready to cut losses fast.” As millionaire penny stock trader and teacher Tim Sykes, says, “Consistency is key in trading; don’t let emotions dictate your trades.”. APP is giving the market plenty of catalysts; it’s on traders to manage the risk.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:

Leave a reply