Glaukos Corporation stocks have been trading up by 32.65 percent following bullish sentiment on its glaucoma treatment pipeline.
Key Takeaways
- Q3 EPS landed at $0.47 versus roughly -$0.09 to -$0.10 expected, with revenue near $211M versus $168M, sending GKOS up about 14% on strong glaucoma and ophthalmic product momentum.
- Management guided 2026 net sales to $775M–$785M and 2027 revenue to $1.0B, well ahead of Street views around $692M and $852.5M, reinforcing a powerful growth path.
- Positive Phase 4 iDose TR data with cataract surgery showed statistically significant extra intraocular pressure reduction and a clean safety profile, supporting broader glaucoma adoption.
- Three‑year Phase 3 extension data for Epioxa in keratoconus showed durable vision gains and a clean long‑term safety profile after a single treatment, backing its corneal franchise potential.
- An exclusive RevOpsis deal brought RO‑104 and the RevMod biologics platform into the GKOS retinal pipeline, expanding longer‑term optionality in major eye‑disease markets.
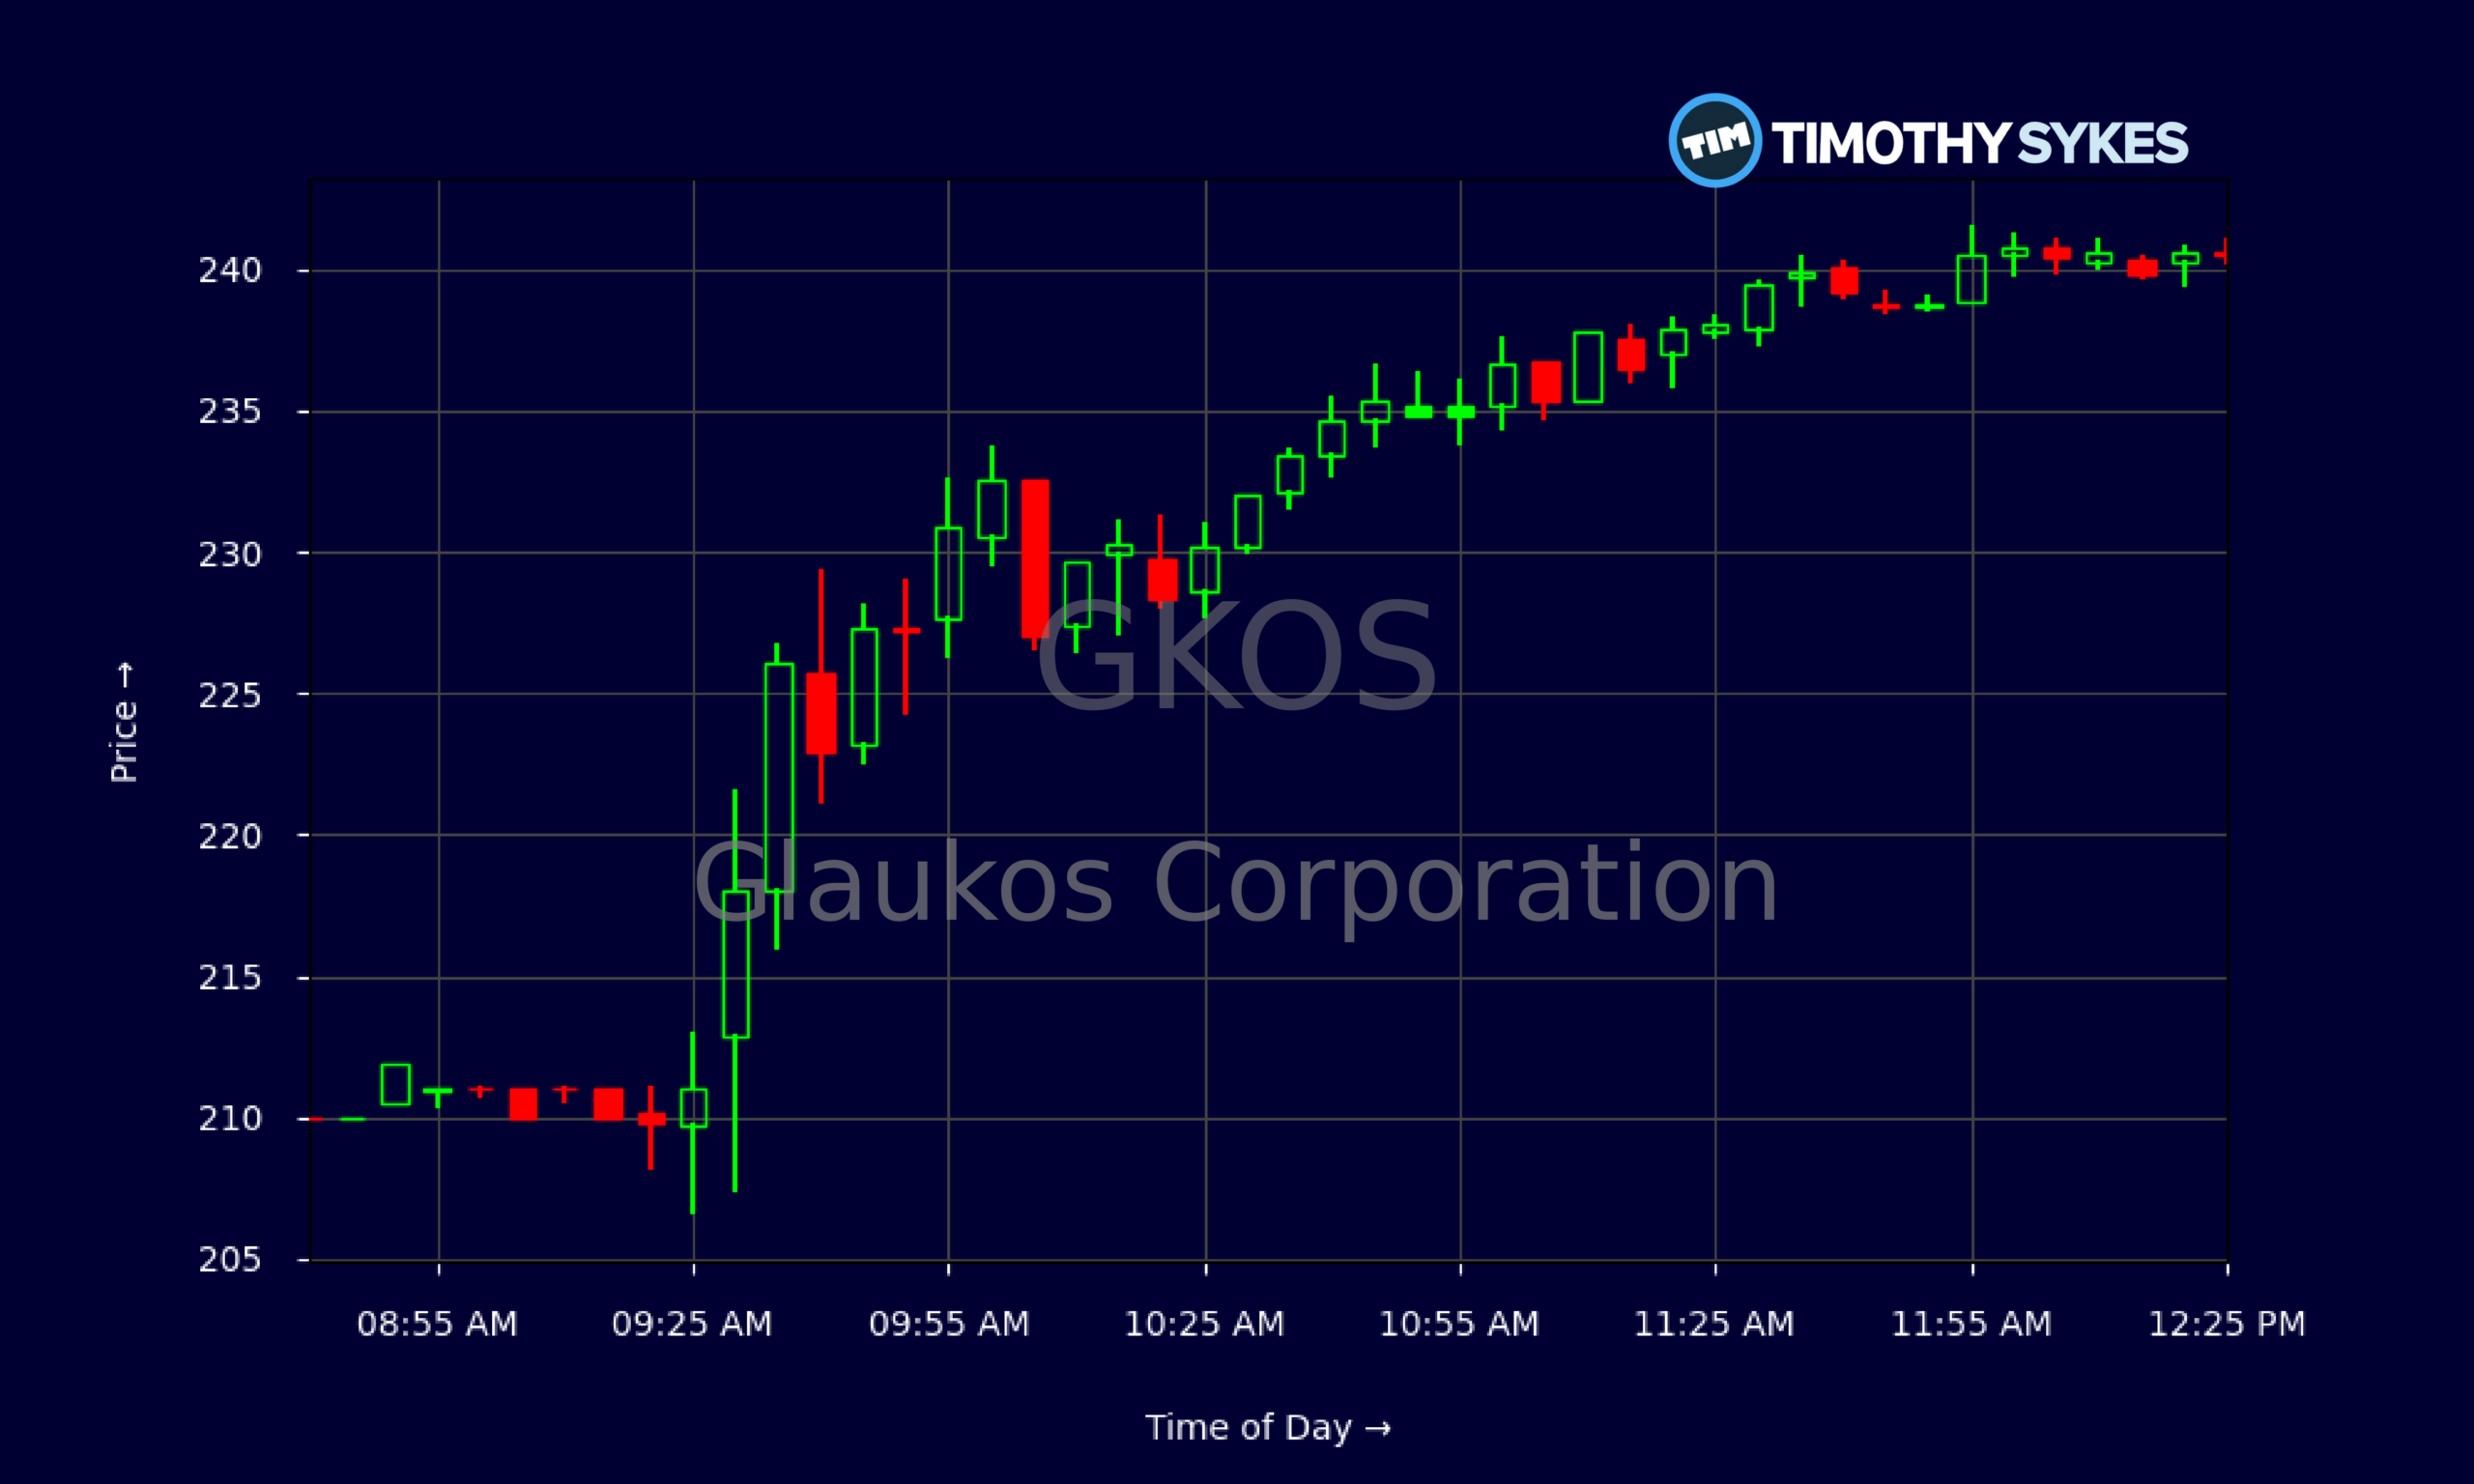
Live Update At 12:32:28 EDT: On Thursday, October 29, 2026 Glaukos Corporation stock [NYSE: GKOS] is trending up by 32.65%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
GKOS has shifted from a quiet grind higher to a full-on momentum story on the chart. After closing at $181.43 on 2026/10/28, Glaukos ripped to a $240.52 close on 2026/10/29. That’s roughly a 33% one‑day surge, fueled by the Q3 earnings beat and bullish multi‑year guidance.
Intraday action in GKOS shows classic high‑volume trend behavior. The stock opened around $212.83, flushed to $207.41, then quickly reclaimed the low $220s, grinding higher all day and tagging an intraday high near $241.47. For short‑term traders, that steady staircase move with higher lows is the textbook sign of strong demand overwhelming supply.
Fundamentally, Glaukos is still a high‑growth, high‑valuation name. Revenue over the last year sits around $507.4M, with revenue growth running in the mid‑20% range. Margins are still negative at the bottom line, but gross margin is a hefty 60.7%, which tells traders GKOS has room to scale into profitability if operating costs come under control.
More Breaking News
The balance sheet looks solid. A current ratio near 5 and low debt‑to‑equity around 0.15 give Glaukos financial flexibility to keep funding its ophthalmic pipeline. For traders, that combination of strong top‑line growth, premium margins, and clean liquidity often supports sustained momentum when good news hits.
Why Traders Are Watching GKOS Momentum
GKOS is on many day‑traders’ and swing‑traders’ screens for one simple reason: the company just crushed expectations and backed it up with big numbers for the future. Glaukos reported Q3 adjusted EPS of $0.47 when the Street was braced for a loss near -$0.09 to -$0.10. Revenue came in around $211M versus a $168M consensus. That’s not a small beat — it’s a trend‑changing surprise.
The market reaction said it all. GKOS jumped about 14% after the print, then followed through with heavy volume and a clean uptrend intraday. This is exactly the kind of earnings‑plus‑guidance catalyst that Tim Sykes’ community studies over and over: clear news, clear numbers, and clear price confirmation.
Glaukos management then laid out an aggressive road map. Net sales guidance for 2026 sits at $775M–$785M versus about $691.7M expected. For 2027, GKOS is targeting $1.0B in revenue, far above the roughly $852.5M current consensus. Traders see that billion‑dollar marker as a psychological and fundamental milestone — it helps justify why GKOS trades at a premium price‑to‑sales multiple.
The Street is responding. BTIG lifted its GKOS price target to $205 and kept a Buy rating, while Mizuho nudged its target to $190 and reiterated Outperform, even as it flagged potential procedure volume headwinds from broader health‑policy shifts. For momentum traders, that kind of supportive analyst backdrop often fuels dip‑buying behavior when GKOS pulls back intraday or in coming weeks.
On the clinical side, the story is also stacking up. Phase 4 topline data showed the iDose TR implant, when used with cataract surgery, delivered statistically significant and clinically meaningful extra intraocular pressure reduction versus surgery alone, and hit all primary and key secondary endpoints with a favorable safety profile. That supports iDose TR as a durable glaucoma growth engine for Glaukos.
Add in three‑year Phase 3 extension data for Epioxa in keratoconus — showing sustained improvements in corneal curvature, meaningful visual acuity gains, and no need for repeat intervention — and GKOS now has more than one credible franchise driving the bull case.
Conclusion
For active traders, GKOS is a live case study in how strong fundamentals can ignite a powerful technical breakout. Glaukos delivered a shock Q3 beat, printed $0.47 in EPS against an expected loss, and posted revenue near $211M versus $168M consensus. Then management doubled down with 2026 guidance of $775M–$785M and a 2027 revenue goal of $1.0B, all while the stock ripped from the $180s into the $240 area.
Under the hood, the product engine looks real. GKOS is leaning on iDose TR in glaucoma, with Phase 4 data confirming extra pressure reduction and clean short‑term safety when paired with cataract surgery. Epioxa’s three‑year durability and safety data in keratoconus points to a one‑time, high‑value corneal treatment that doctors and payers may embrace. The RevOpsis deal adds RO‑104 and the RevMod platform, giving Glaukos a longer‑dated retinal pipeline on top of its current franchises.
At the same time, traders need to remember the other side of the coin. GKOS still runs negative net margins, and Mizuho’s note about possible procedure volume pressure from Affordable Care Act and Medicaid trends is a reminder that even strong stories face macro risks. Volatility after such a big move can be sharp. As millionaire penny stock trader and teacher Tim Sykes, says, “There is always another play around the corner; don’t chase just because you feel FOMO.”. That mindset helps traders stay disciplined when a chart has already made a huge move and the temptation is to chase.
That’s why Tim Sykes’ core rule — “cut losses quickly” — matters so much when trading names like GKOS. The setup right now is powerful: breakout chart, bullish news, big guidance, and strong Street support. But as always, it’s on each trader to manage risk, study the GKOS chart, track the news flow, and treat this move as an educational example — not a guarantee of what comes next.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply