Donnelley Financial Solutions Inc. stocks have been trading up by 9.6 percent after upbeat earnings and guidance lifted investor confidence.
What Traders Need To Know
- Q3 adjusted EPS hit $1.07, beating the $0.84 consensus and $0.86 last year, with net sales at $185M versus $179.9M expected.
- Q4 net sales guidance of $175M–$180M came in ahead of the $170.9M Street view, with implied adjusted EBITDA margins of 26%–27%.
- Software net sales rose 5% year over year, with ActiveDisclosure up about 24% and software now about 51.5% of total net sales.
- Needham lifted its DFIN price target to $72 from $60 and reaffirmed a Buy rating following the Q3 beat and software strength.
- A new Venue MCP Connector product links AI assistants like Microsoft Copilot to Venue data rooms, tightening DFIN’s capital markets workflow story.
Weekly Update Oct 26 – Oct 30, 2026: On Saturday, October 31, 2026 Donnelley Financial Solutions Inc. stock [NYSE: DFIN] is trending up by 9.6%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Technology industry expert:
Analyst sentiment – positive
DFIN occupies a defensible niche at the intersection of regulatory compliance, capital markets workflows, and SaaS disclosure, with software now exceeding half of net sales. Despite a shrinking legacy print base (3–5 year revenue CAGR negative), current gross margin of 64% and EBITDA margin of 16–17% underscore a profitable, asset‑light mix. Q3 revenue of $185M and net income of $21.3M imply annualized ROE >20% and ROA ~10%, supported by moderate leverage (D/E 0.55, interest coverage 9.7x) and robust free cash flow (~$86M Q3 FCF).
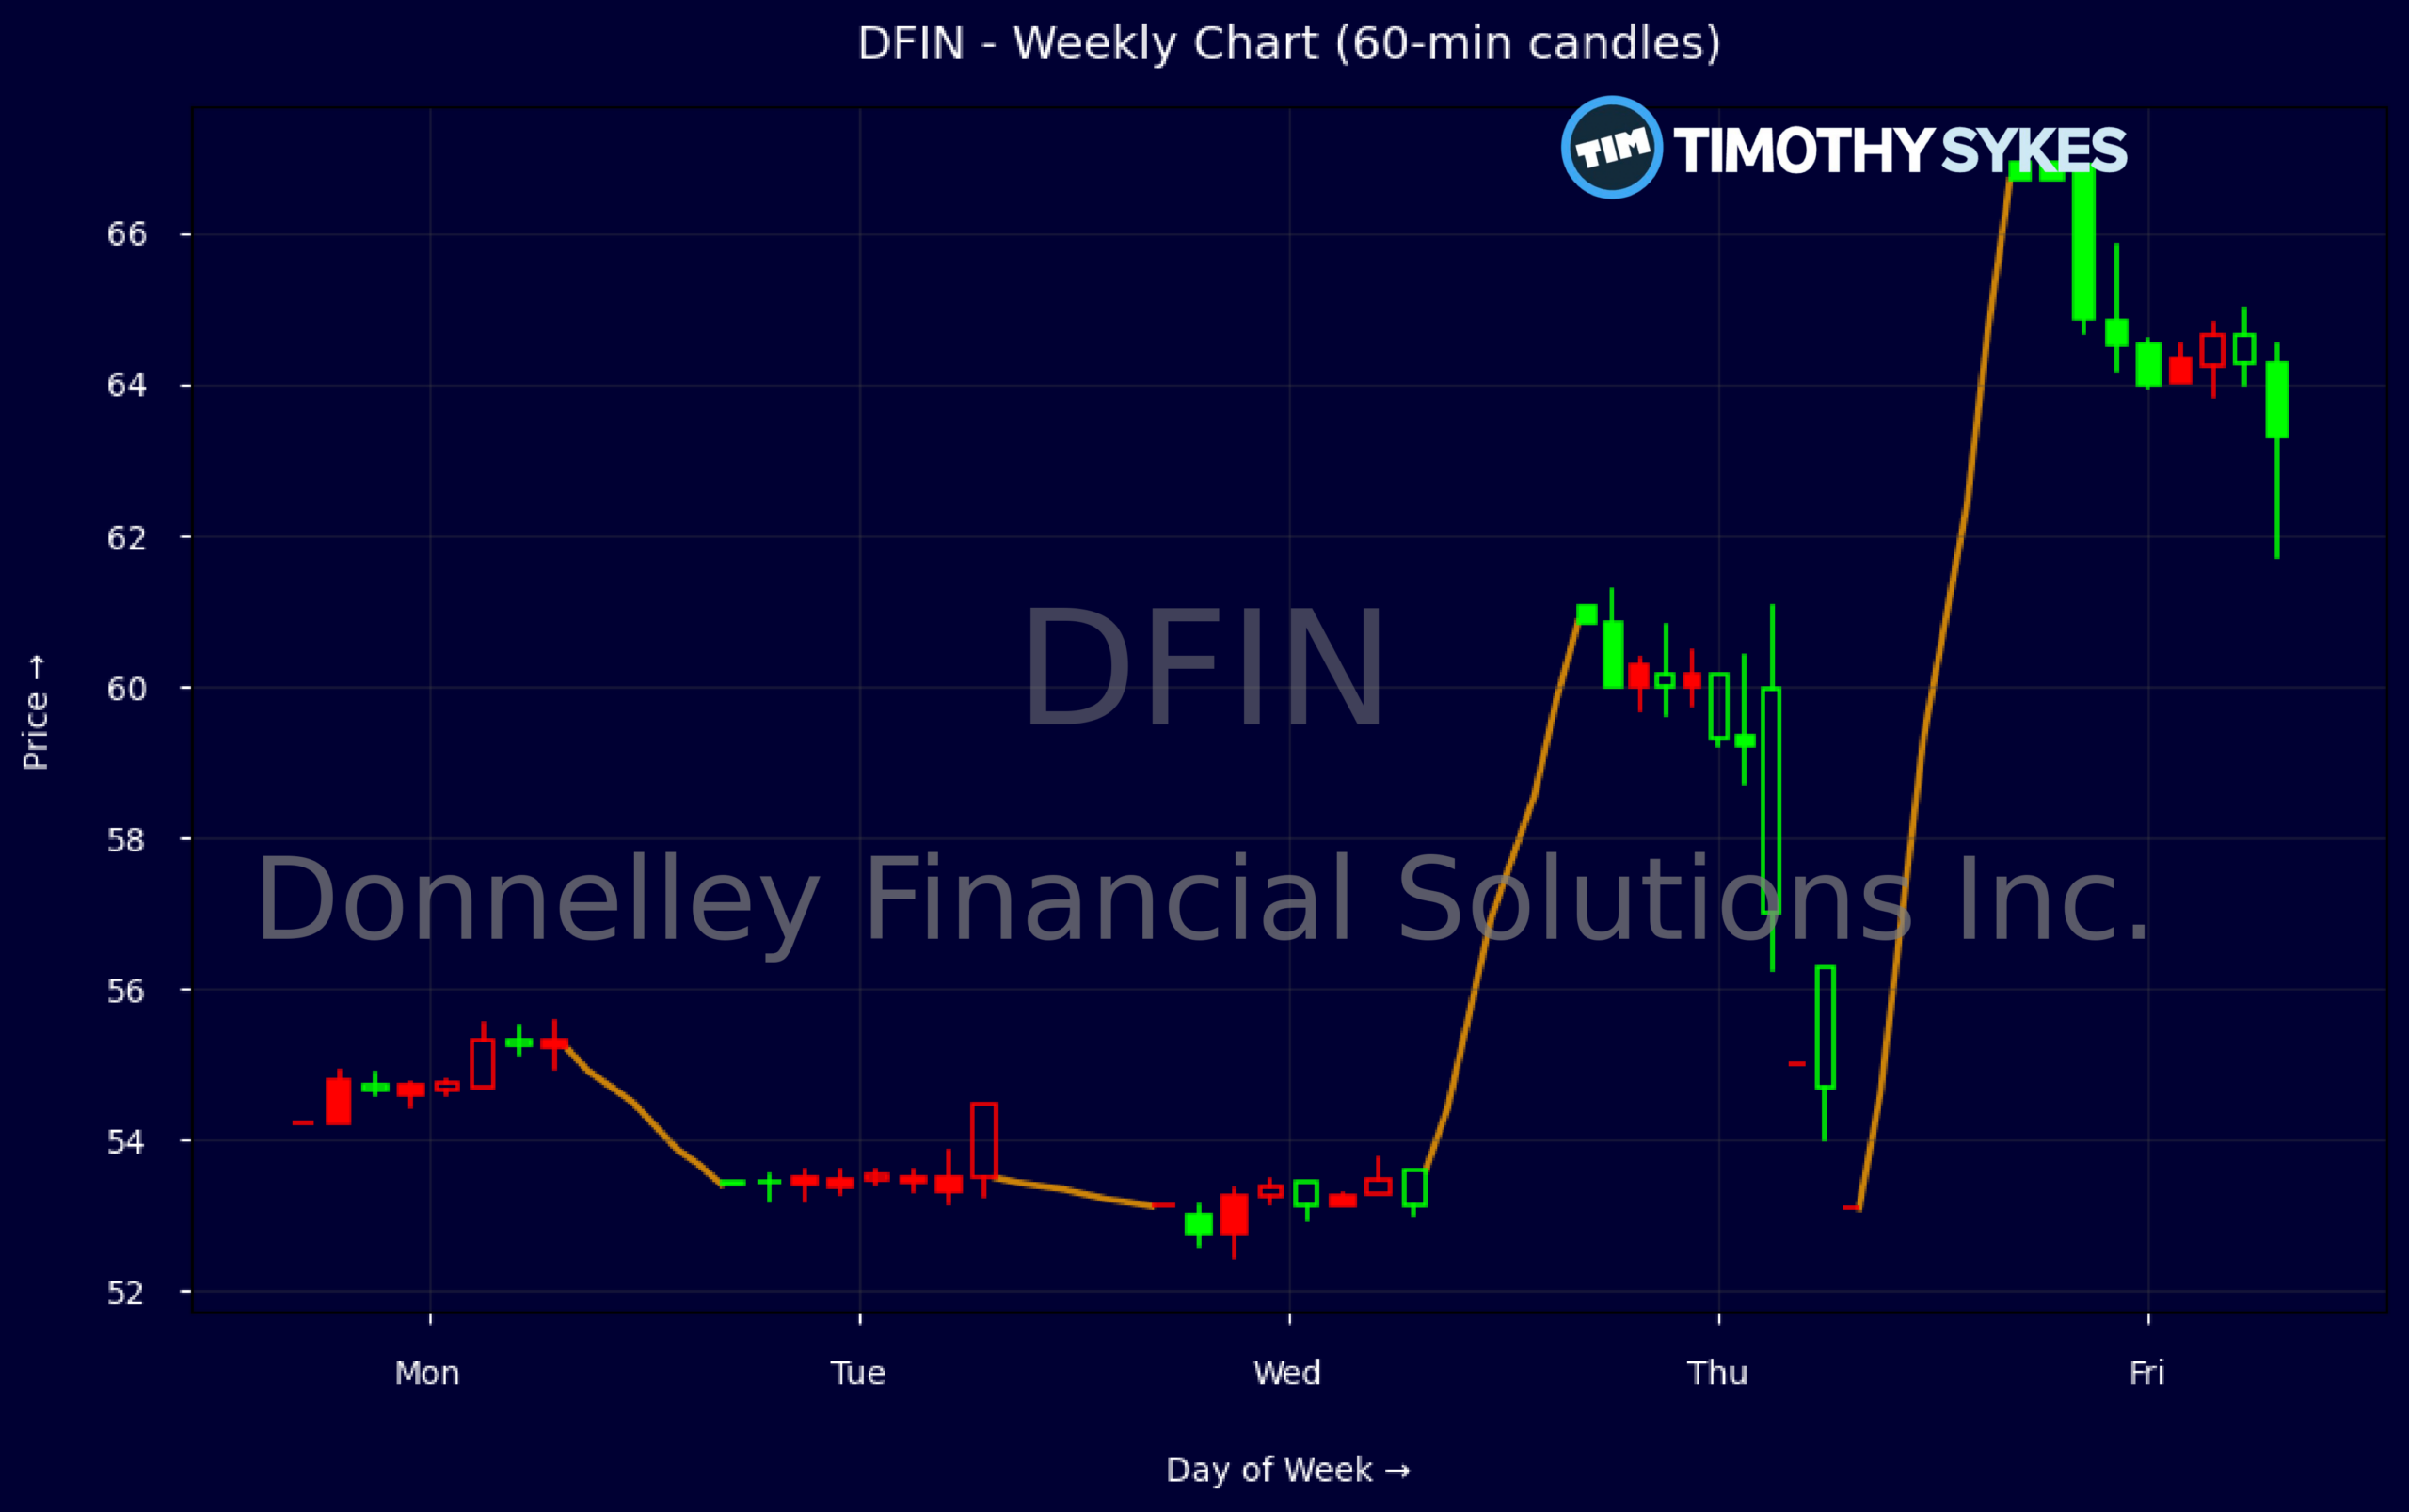
Technically, the stock has broken out sharply: from a tight 53–54 consolidation to 61, then 66.93 in consecutive sessions, a near-25% weekly move that confirms a strong uptrend. Intraday 5‑minute action post-earnings shows sustained buying rather than a blow‑off reversal, with volume concentrated near 60–62, creating a clear demand zone. The actionable trading level is $60: above it, long bias with pullbacks toward 60–62 as entries; a decisive close below 60 would signal failed breakout and justify risk reduction.
Fundamentally and versus Tech / Software & IT Services benchmarks, DFIN screens attractively: high cash conversion (P/FCF ~4.7x), solid mid‑20s adjusted EBITDA margins guided for Q4, and accelerating SaaS growth (ActiveDisclosure +24%, Venue/Arc re‑accelerating). Recent beat‑and‑raise, the AI‑enabled Venue MCP Connector, and Needham’s $72 target support multiple expansion from a current P/E ~32. I see 6–12 month upside toward $72–75, with support at $60 and near‑term resistance in the high‑60s.
More Breaking News
Quick Financial Overview
Donnelley Financial Solutions Inc. (DFIN) just printed the kind of quarter that gets short-term traders’ attention. Q3 revenue landed at $185M, modestly above expectations, but the real story was leverage to the bottom line. Adjusted EPS of $1.07 beat the $0.84 consensus and improved from $0.86 a year ago, backed by a gross margin near 64.2% and EBITDA margin in the mid-teens. Management then raised the near-term bar with Q4 net sales guidance of $175M–$180M and strong 26%–27% adjusted EBITDA margins.
Under the hood, DFIN is shifting further toward higher-margin software. Software solutions net sales grew 5% year over year in Q3, with ActiveDisclosure jumping roughly 24% and pushing software to about 51.5% of total net sales. Key ratios support that mix: a P/E near 31.7 and price-to-sales around 1.53 signal the market is already paying up for earnings and cash generation, helped by free cash flow of about $85.8M for the latest quarter and solid returns on equity above 20%. Balance sheet strength looks reasonable, with total debt-to-equity at 0.55 and current ratio around 1.3.
The chart confirms how traders reacted. On the weekly tape, DFIN went from the low-$50s to a close near $66.93, with the big gap day around 2026/10/29 as price ripped from roughly $53 to above $61 on the earnings release. An intraday 5-minute snapshot shows a session range from about $61.71 to $66.89, closing at the high, which is classic trend-day behavior when shorts are covering and momentum players are piling in. With Needham boosting its target to $72 on the heels of the beat and guidance, the stock is now trading with a clear momentum tailwind rather than a value setup.
Conclusion
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply